

The dollar index steadied around 102 on Tuesday, near its highest since April 2025, as the euro weakened on French fiscal and political concerns and Spain's upcoming snap election, yet stabilized near 1.1220 after touching its lowest level since May 2025.
Sterling recovered above 1.32 as Fed rate hike bets eased. Gold remained below $4,140 and silver traded under $61 as Treasury yields near 24-year highs limited demand for precious metals. Meanwhile, the yen held near 157.9 as investors awaited Japanese wage and spending data for clues on the Bank of Japan’s next move.
| Time | Cur. | Event | Forecast | Previous |
| All Day | CNH | China - National Day | - | - |
| 12:30 | USD | Trade Balance (Aug) | -102B | -88.60B |
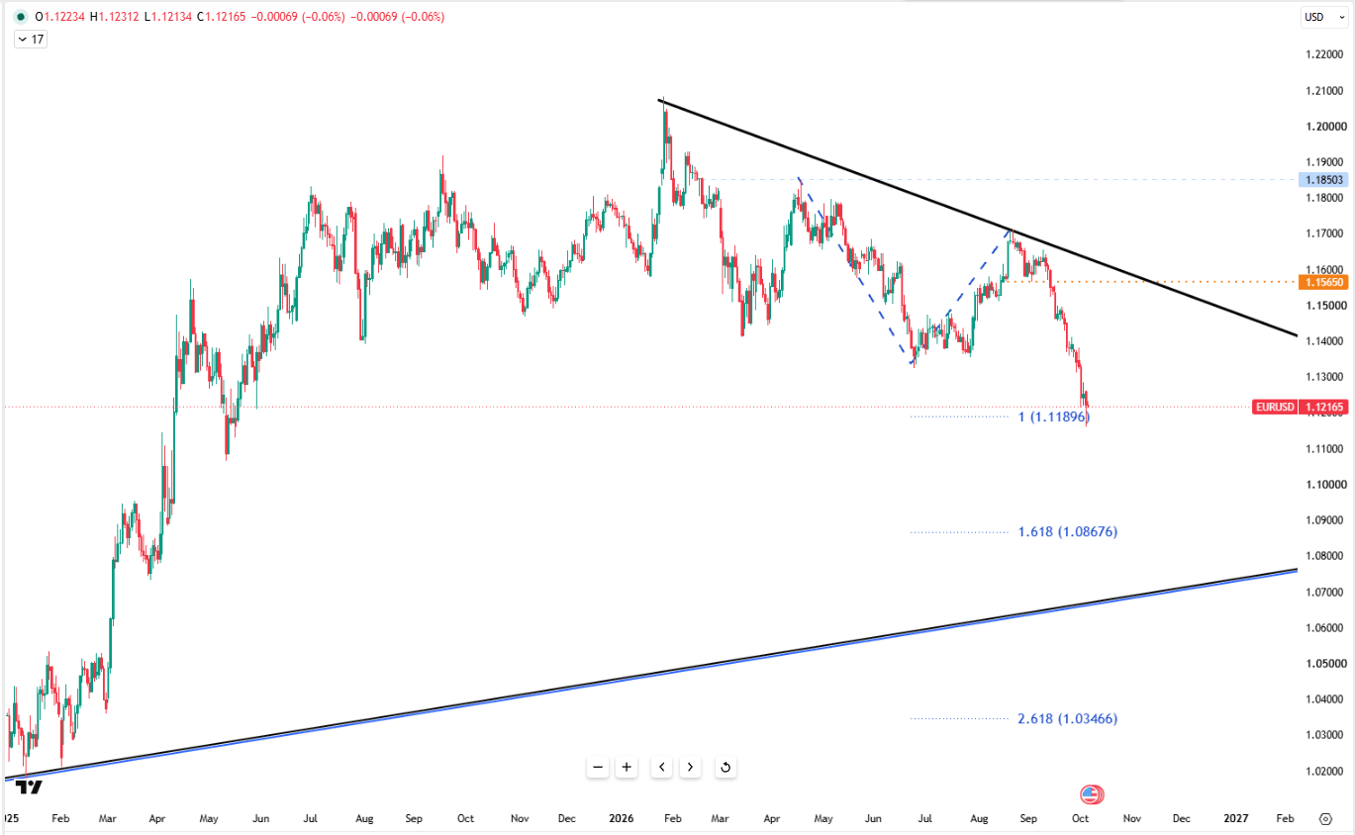
EUR/USD hovered around 1.1221 Tuesday morning, steadying after touching 1.1162 on Monday, its lowest level since May 2025. Political uncertainty from Spain's snap election, rising French borrowing costs, and September Eurozone inflation ticking up to 3.8% continued to weigh on European sentiment, while a resilient US dollar maintained its broader strength despite soft US employment data.
The first resistance is positioned at 1.1260 while the support starts from 1.1190.
| R1: 1.1260 | S1: 1.1190 |
| R2: 1.1290 | S2: 1.1160 |
| R3: 1.1320 | S3: 1.1080 |
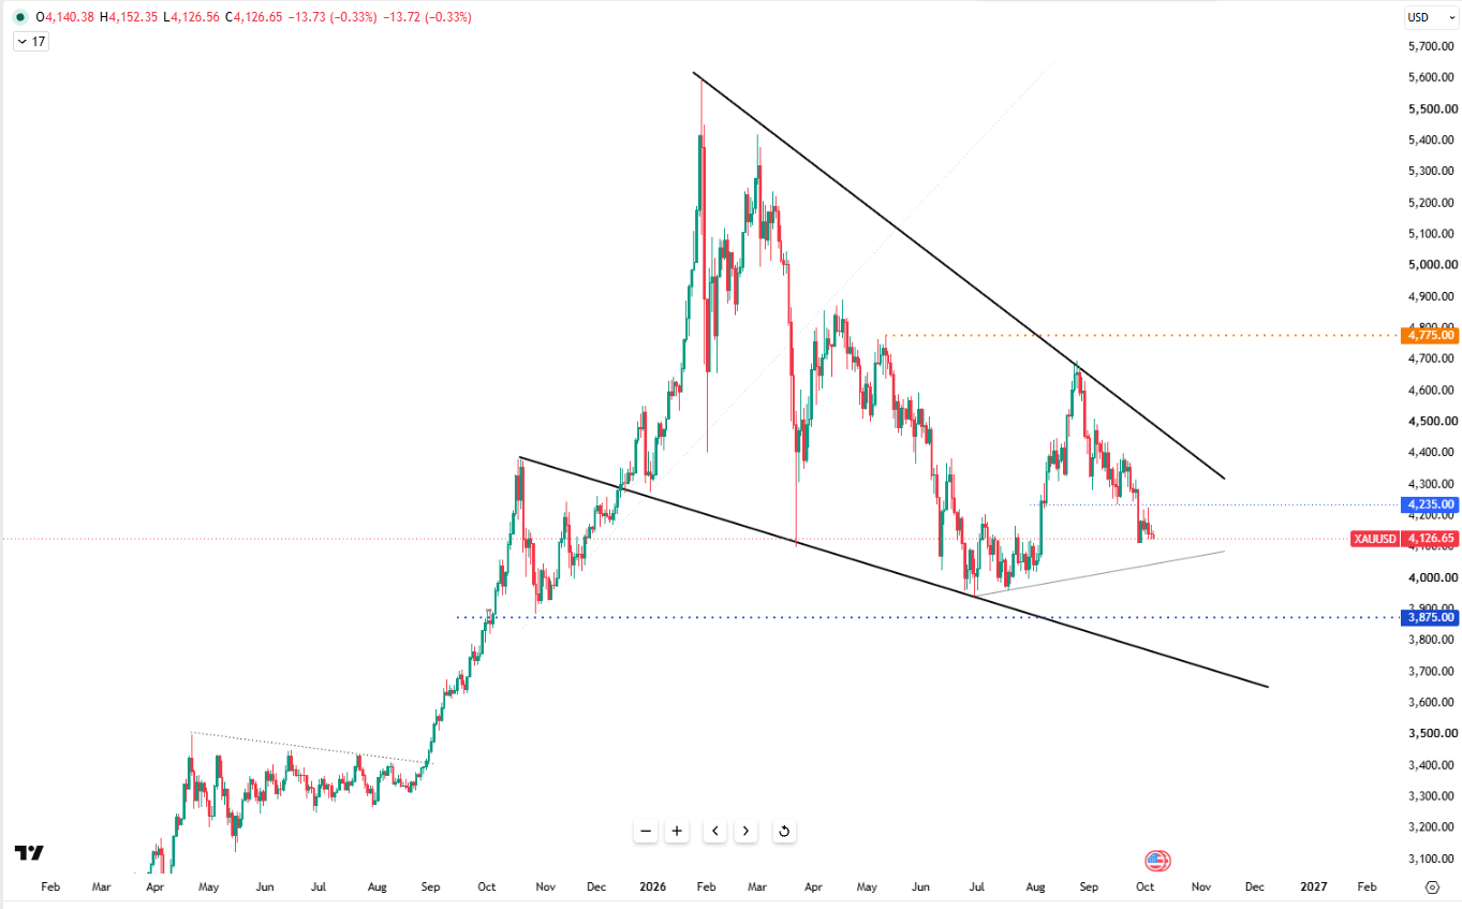
Gold remained under $4,140 per ounce on Tuesday, holding near two-month lows as a strong US dollar and Treasury yields hovering near 24-year highs counteracted support from weak employment data. European fiscal and political headwinds dragged the euro down, reinforcing dollar strength. Markets now price a 78% probability of a Fed pause, while softening crude oil prices moderated inflation concerns.
First resistance is seen at $4155, with initial support near $4100.
| R1: 4155 | S1: 4100 |
| R2: 4200 | S2: 4060 |
| R3: 4240 | S3: 4000 |
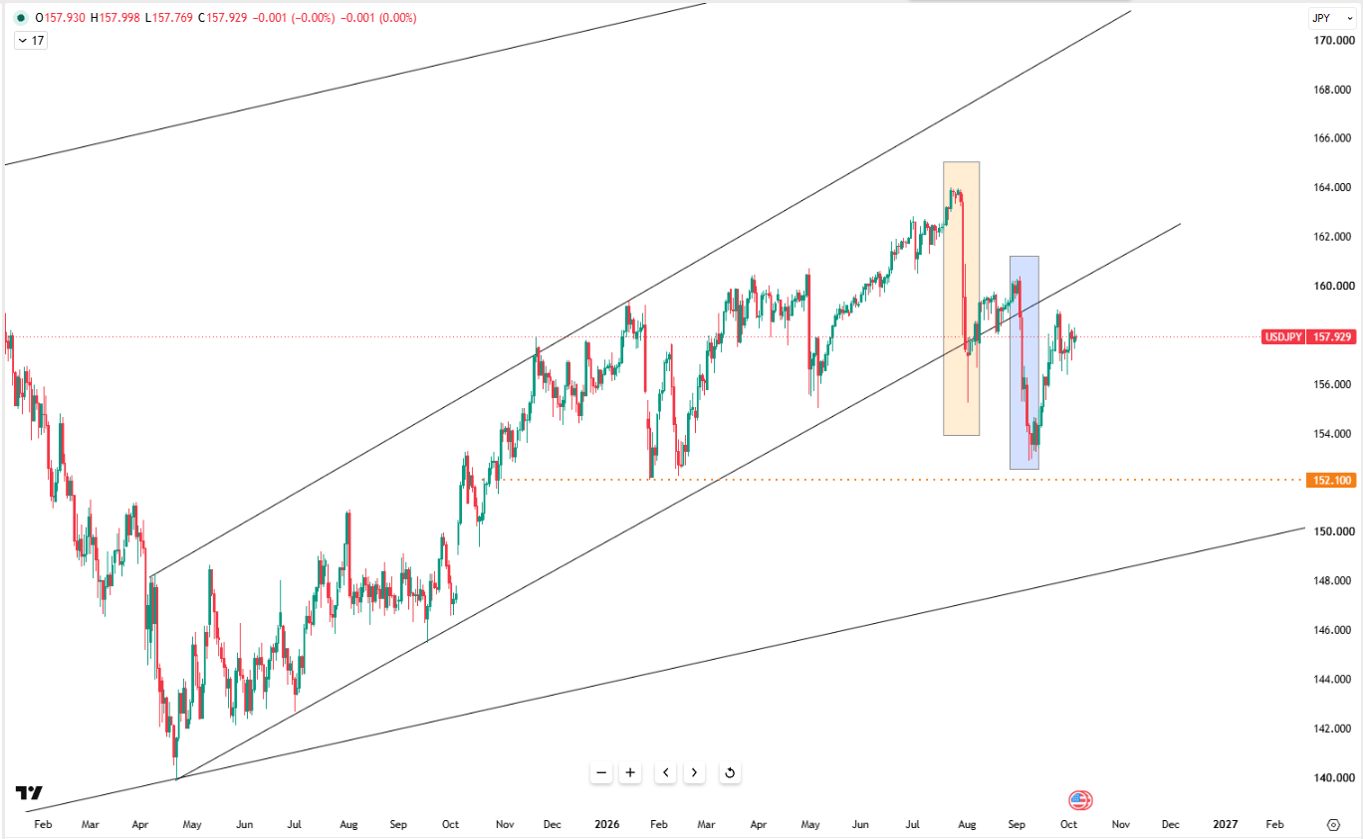
The Japanese yen hovered around 157.9 per dollar on Tuesday as Prime Minister Sanae Takaichi pursued her expansionary fiscal agenda, proposing a food consumption tax cut funded without issuing new bonds. Investors are awaiting key domestic wage and spending figures, while hawkish notes in the Bank of Japan’s September summary kept expectations alive for another rate increase this year.
First resistance is seen at 158.50, with initial support near 156.80.
| R1: 158.50 | S1: 156.80 |
| R2: 160.10 | S2: 154.40 |
| R3: 162.50 | S3: 152.60 |
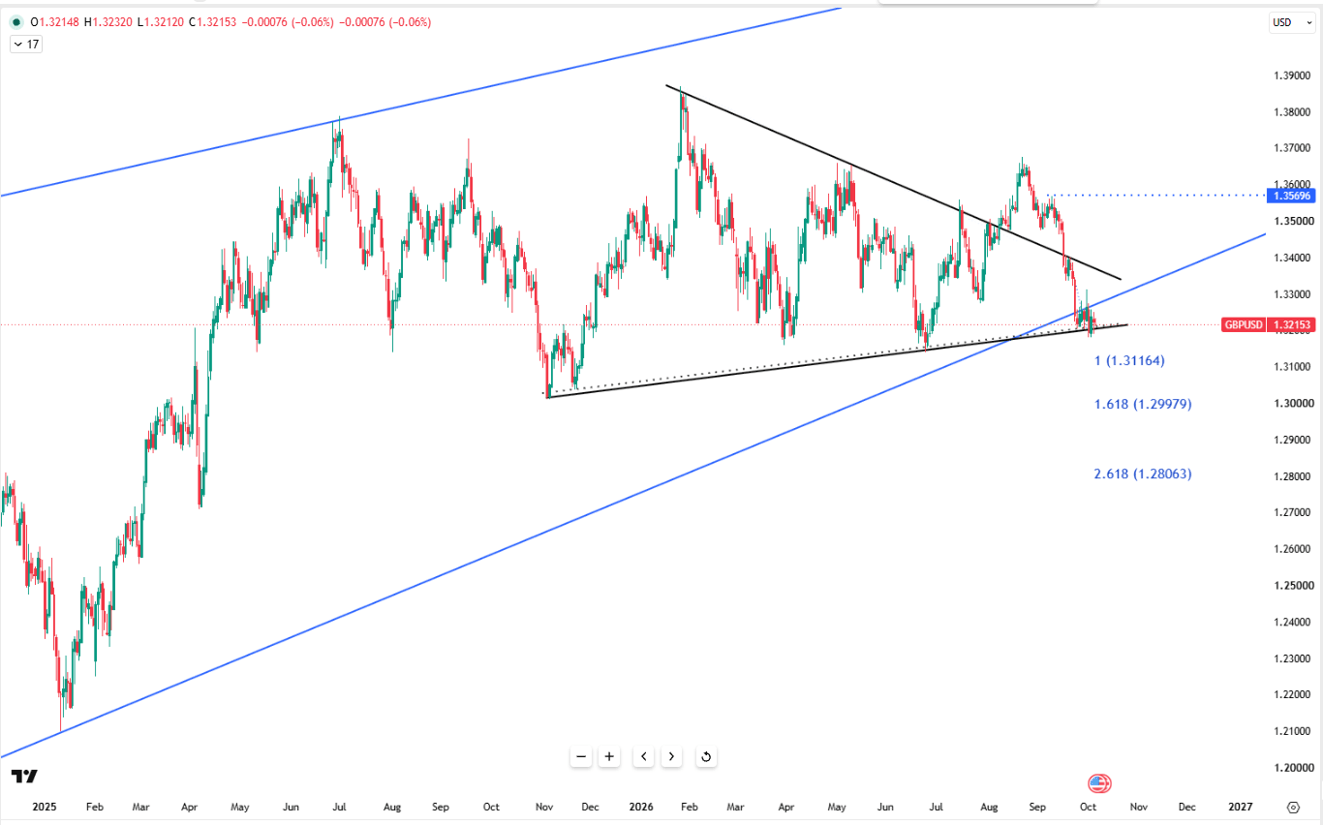
Sterling held above $1.32 on Tuesday, rebounding from three-month lows after weak US non-farm payrolls data, showing just 29,000 September additions versus 90,000 expected, reduced Federal Reserve rate hike bets. Meanwhile, expectations for roughly 30 basis points of Bank of England tightening by year-end due to energy-driven inflation risks and pro-EU comments from Prime Minister Andy Burnham provided support.
From a technical view, resistance stands near 1.3340, with support around 1.3140.
| R1: 1.3340 | S1: 1.3140 |
| R2: 1.3350 | S2: 1.3100 |
| R3: 1.3400 | S3: 1.3050 |
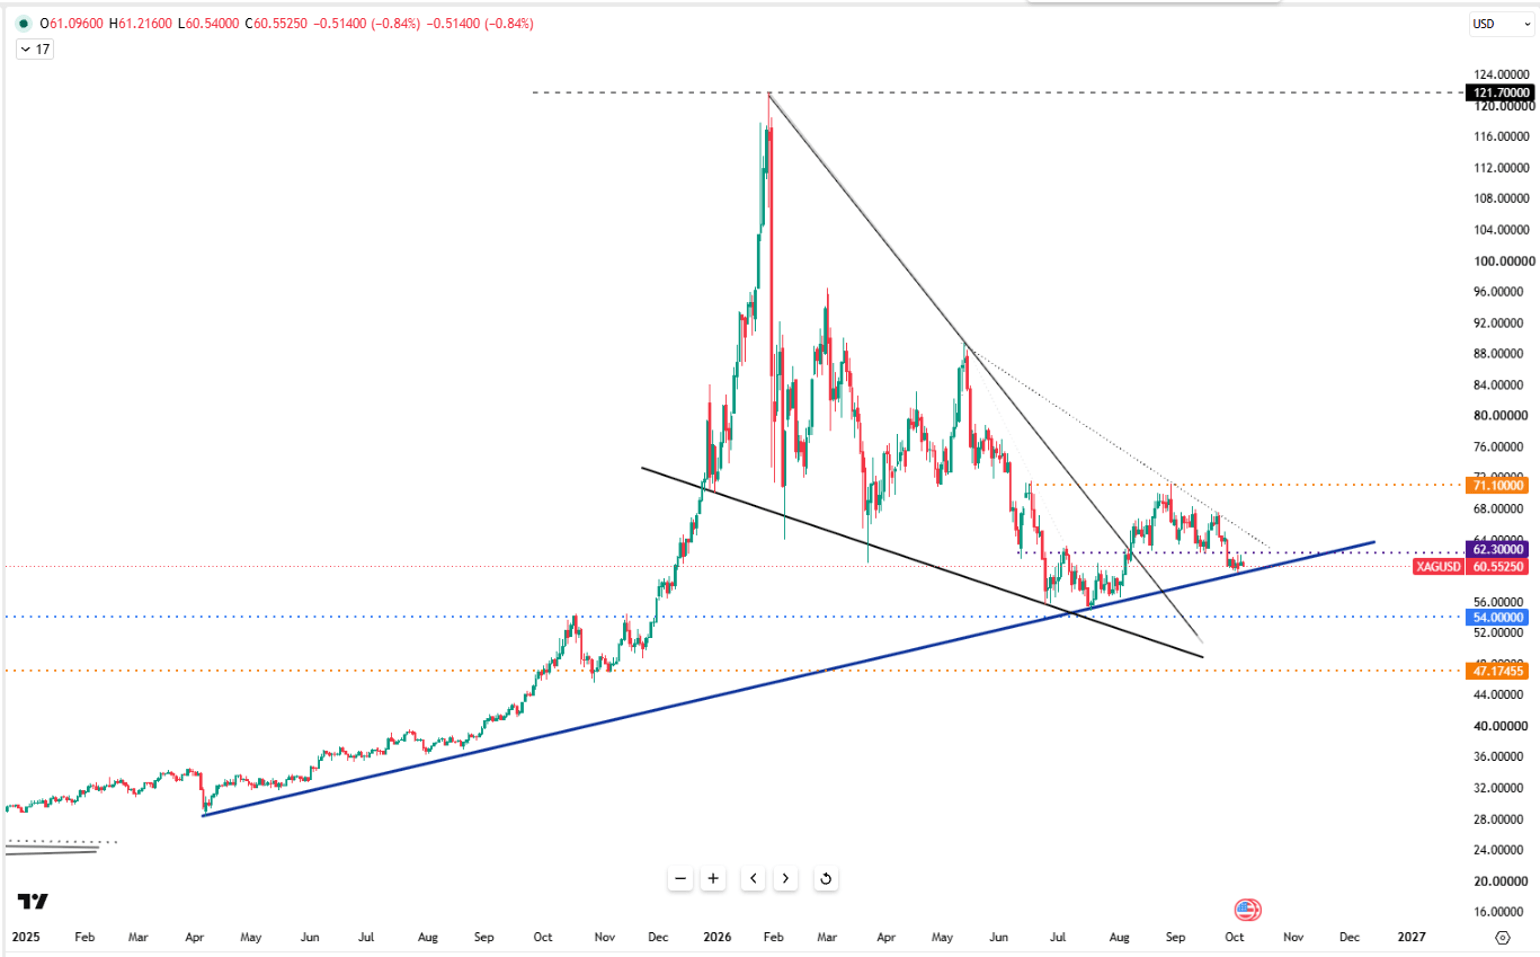
Silver traded below $61 per ounce on Tuesday, holding near two-month lows as a firmer dollar and Treasury yields at 24-year highs outweighed support from soft labor data. Weakness in the euro due to European political and fiscal concerns supported the dollar. Markets price a 78% chance of a Fed pause, while declining crude prices eased inflation fears.
From a technical view, resistance stands near $62.50, while support is located around $60.00.
| R1: 62.50 | S1: 60.00 |
| R2: 64.20 | S2: 59.60 |
| R3: 65.30 | S3: 57.50 |
 Wall Street’s Triple Test: Rates, Growth and AI
The Fed’s rate decision, US GDP and inflation data, and Big Tech earnings put economic growth and AI investment returns to the test.
Detail Markets Await Rate Decisions (10.27.2026)Easing oil prices offered some relief to precious metals ahead of major central bank policy decisions, with gold stabilizing near $4,005 and silver holding around $53 after recent declines.
Detail CB Decisions Loom Amid Geopolitical Risks (26 – 30 October)
Financial markets entered the week cautiously as investors prepared for monetary policy decisions from the Federal Reserve, European Central Bank, and Bank of Japan. The Dollar Index eased toward 101.6, while Treasury yields continued to retreat from recent highs. All three central banks are expected to leave rates unchanged this week, although persistent inflation and elevated energy prices have kept expectations for further tightening alive. Attention is also turning to US GDP, PCE inflation, and major technology earnings for fresh signals on economic growth.
DetailThen Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


