

Markets showed cautious strength in early August as expectations for U.S. interest rate cuts continued to grow following weaker labor data and renewed tariff threats.
The euro pushed above $1.16 with the Fed expected to act ahead of the ECB, while gold and silver reached multi-week highs amid safe-haven demand. The yen held steady after the Bank of Japan flagged inflation risks despite falling real wages. Meanwhile, the British pound recovered slightly ahead of the Bank of England's expected rate cut.
| Time | Cur. | Event | Forecast | Previous |
| 11:00 | GBP | BoE Interest Rate Decision (Aug) | %4.0 | %4.25 |
| 12:30 | USD | Initial Jobless Claimless | 221K | 218K |
| 17:00 | USD | 30-Year Bond Auction | - | 4.889% |
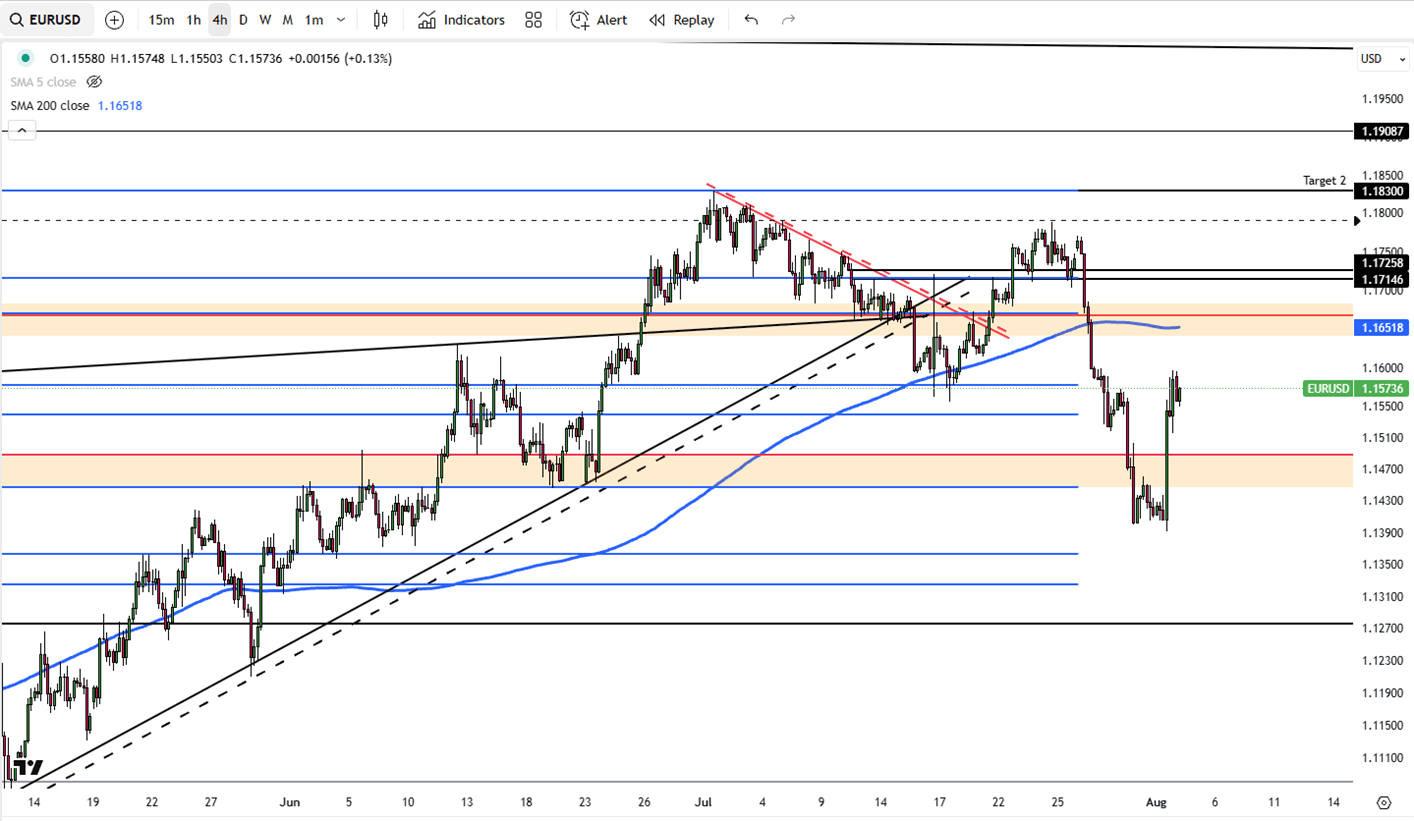
The euro climbed above $1.16 in early August, recovering from a recent low, as investors anticipated rate cuts from both the Federal Reserve and the European Central Bank, with the Fed expected to move sooner. Softer U.S. employment data increased expectations for a Fed rate cut by September. At the same time, markets are pricing in a 60% likelihood of an ECB cut by year-end. Eurozone inflation remained steady at 2.0% in July, slightly above forecasts.
EUR/USD now eyes resistance at 1.1695, while support holds at 1.1590.
| R1: 1.1695 | S1: 1.1590 |
| R2: 1.1725 | S2: 1.1500 |
| R3: 1.1830 | S3: 1.1350 |
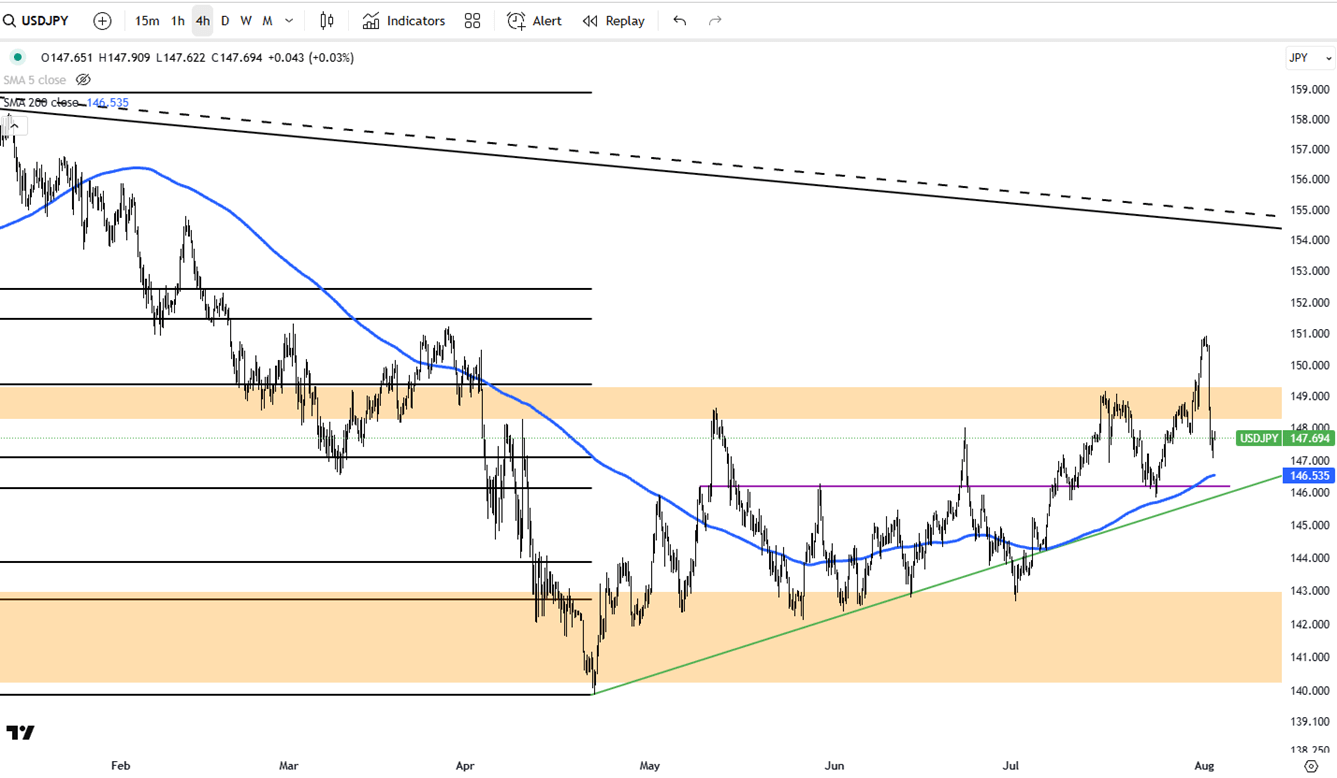
The yen hovered around 147.5 per dollar as markets assessed the Bank of Japan’s policy outlook. While the BOJ held rates steady last week, it raised its inflation forecast and noted global risks. June meeting minutes showed openness to further tightening if conditions improve. Meanwhile, Japan’s real wages fell for a sixth straight month, with inflation still outpacing earnings.
USD/JPY faces resistance at 148.50, with support at 146.00.
| R1: 148.50 | S1: 146.00 |
| R2: 151.50 | S2: 143.00 |
| R3: 152.40 | S3: 140.00 |
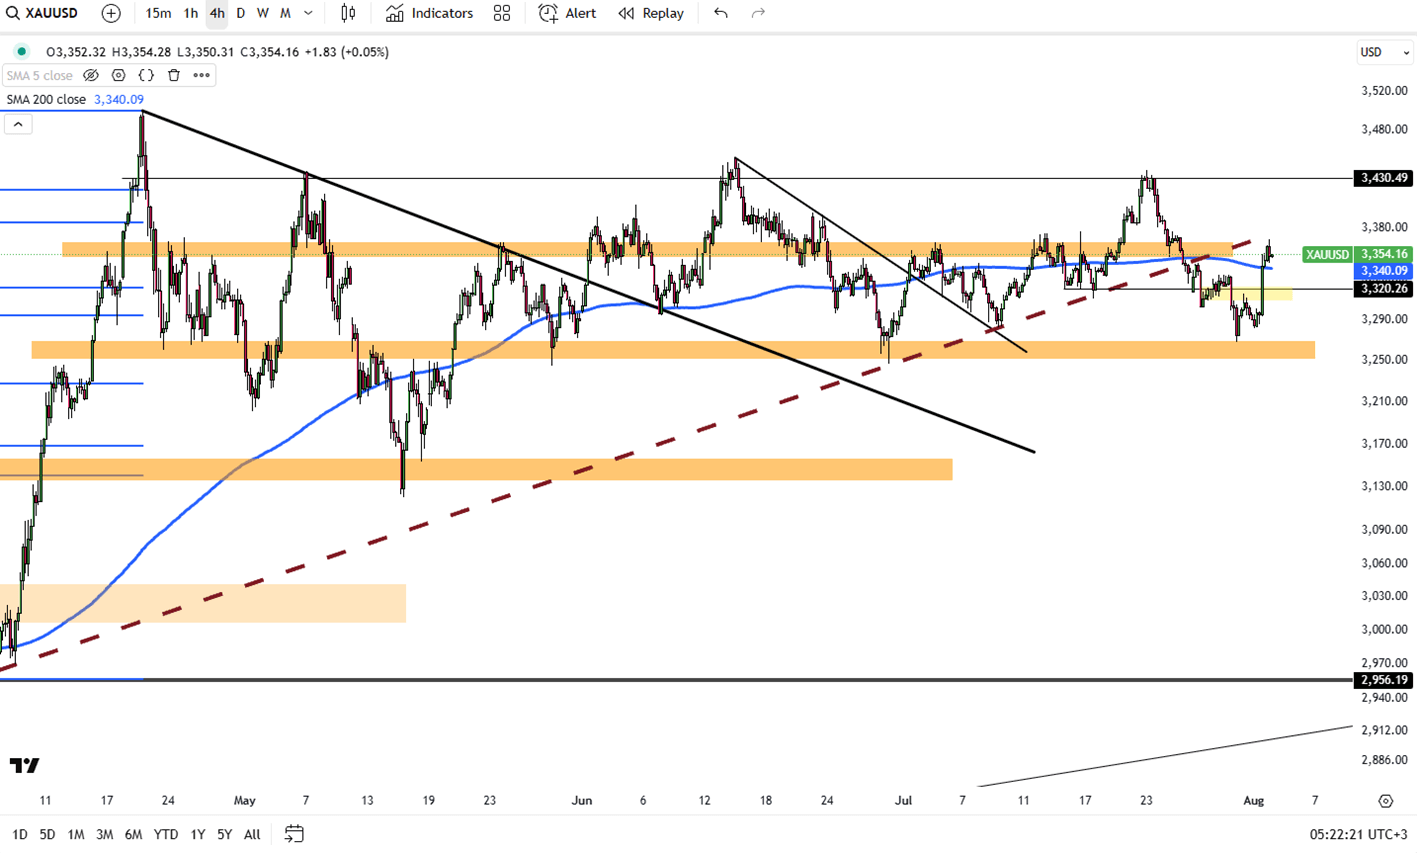
Gold rose toward $3,380 per ounce, reaching a two-week high, as renewed U.S. tariff threats and growing expectations of Fed rate cuts supported demand. President Trump announced significant new tariffs on semiconductors, as well as imports from India and Brazil. Soft U.S. economic data and signs of labor market weakness increased the likelihood of rate cuts in September and December. Trump also plans to nominate a new Fed Governor and is considering replacing Chair Powell, raising concerns about the Fed’s independence.
Gold is testing resistance at $3,400, with support at $3,340.
| R1: 3400 | S1: 3340 |
| R2: 3440 | S2: 3270 |
| R3: 3500 | S3: 3250 |
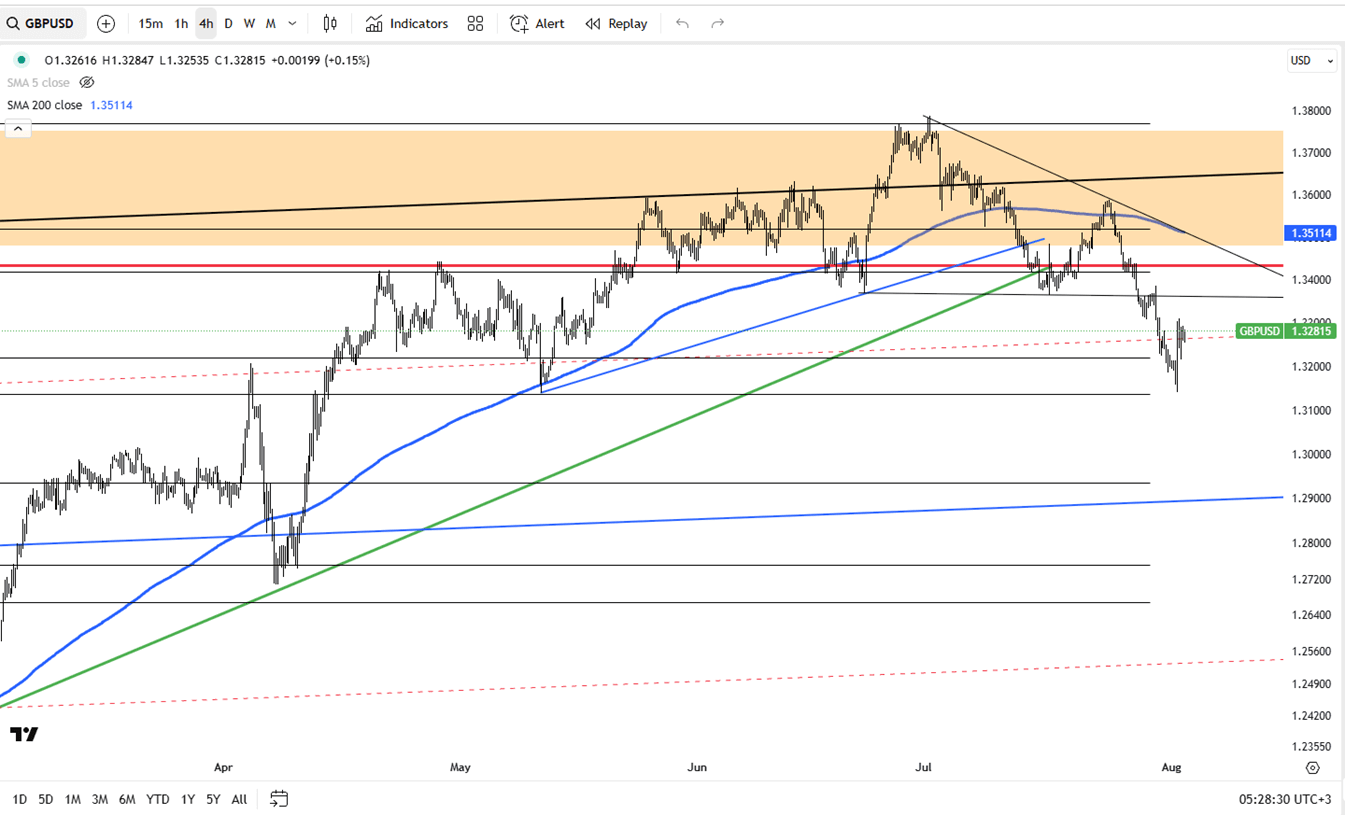
The British pound climbed to $1.328 from an 11-week low of $1.321 after weak U.S. jobs data weighed on the dollar. Despite this recovery, the pound declined by 3.8% in July, marking its worst monthly performance since September 2022, as concerns about the UK economy persisted. Investors now turn their attention to the Bank of England's anticipated 25 basis point rate cut decision today.
GBP/USD is seeing resistance at 1.3330, with initial support at 1.3240.
| R1: 1.3330 | S1: 1.3240 |
| R2: 1.3480 | S2: 1.3140 |
| R3: 1.3600 | S3: 1.3000 |
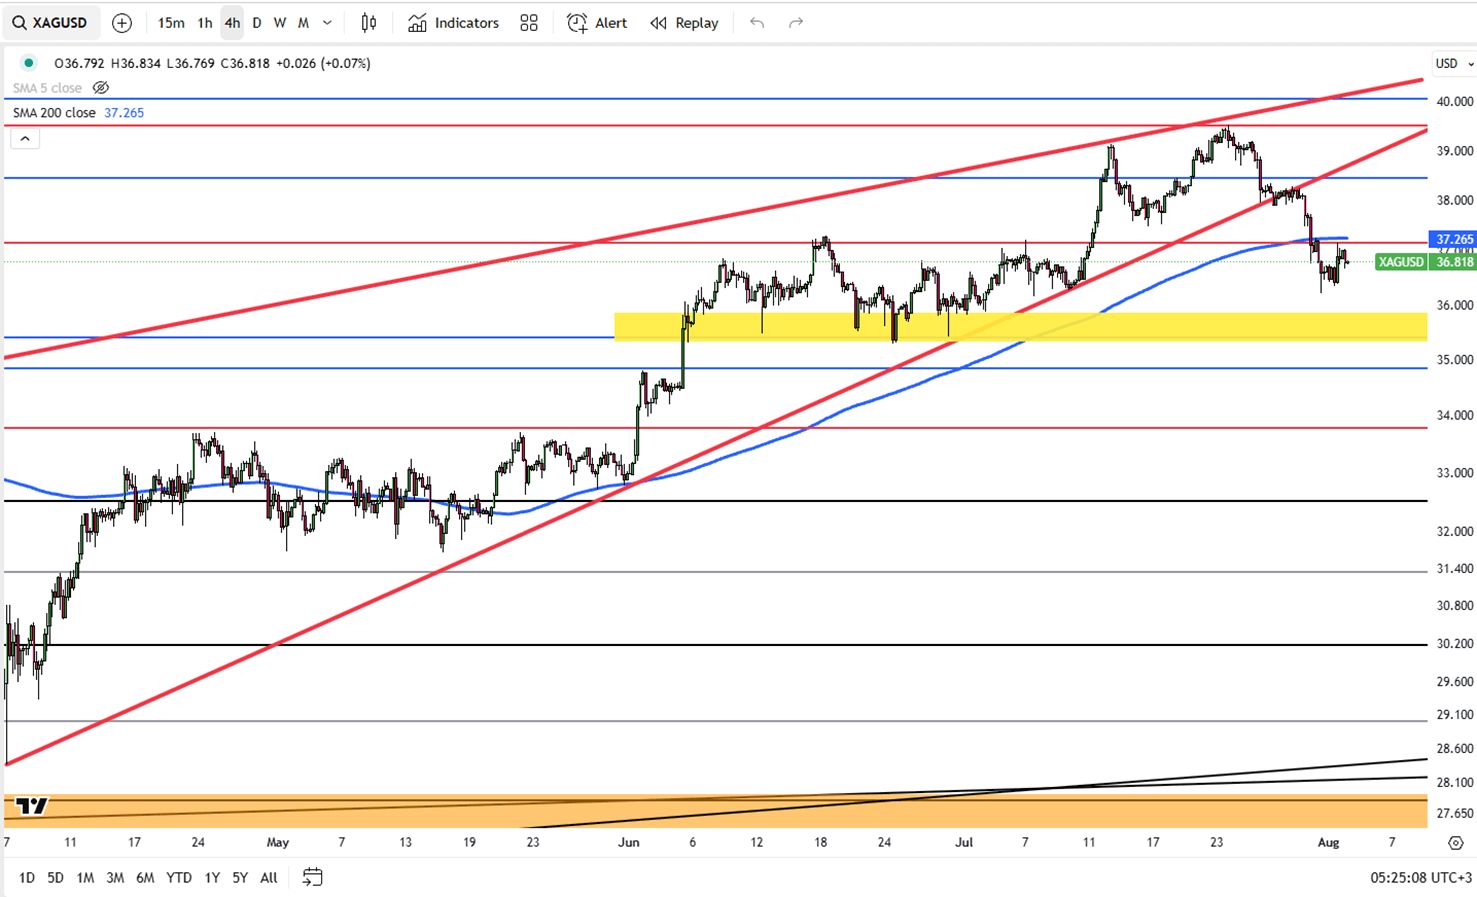
Silver rose above $38 per ounce, reaching a one-week high as expectations for Federal Reserve rate cuts increased, driven by signs of a weakening U.S. labor market. Investors are now looking to jobless claims data for further confirmation. Geopolitical tensions also supported safe-haven demand, as President Trump announced a doubling of tariffs on Indian imports over continued Russian oil purchases and signaled the possibility of meeting with President Putin next week.
Silver is now testing resistance at $38.20, with support holding around $36.50.
| R1: 38.20 | S1: 36.50 |
| R2: 39.50 | S2: 35.50 |
| R3: 40.10 | S3: 33.90 |
 Fed Holds as US Growth and Diplomatic Talks Shape Markets (2 – 6 November)
Financial markets entered November as investors assessed the Federal Reserve's latest policy decision and the outlook for another rate hike in December. The Dollar Index held near 102 after a volatile week, while US Treasury yields remained close to seven-week lows. The Fed kept its benchmark rate at 3.75%–4.00%, citing resilient economic activity and persistent inflation. Markets still assign roughly a 75% probability to a December hike, with attention now turning to October employment figures, ISM surveys, and comments from Fed officials.
Detail Lower Oil Prices Support Metals (11.02.2026)Markets opened the week on a quiet note on Monday following last week’s volatility. Markets continue to price roughly a 75% chance of a Fed rate hike in December.
Strong US economic growth and persistent inflation reinforced expectations for another Federal Reserve rate hike in December, keeping precious metals under pressure.
Then Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


