

Oil inventories are nearing depletion, increasing supply risks and supporting prices. Aramco estimates less than 6 billion barrels remain after over 1 billion barrels were drawn this year, while the IEA is preparing a 100-million-barrel release. The US 10-year Treasury yield stabilized near 5.31% on Wednesday, close to 24-year peaks, as markets awaited the Fed's minutes.
The dollar index stabilized around 102 on Wednesday following Tuesday's losses, with traders awaiting Fed meeting minutes. Gold slipped below $4,150 and silver fell under $61 as the rebound in crude limited support from expectations for a Fed pause. The euro remained near 1.124 amid European fiscal concerns, while sterling consolidated around 1.3250. Meanwhile, the yen weakened toward 158.5 as wide US-Japan yield differentials continued to outweigh expectations for gradual BoJ tightening.
| Time | Cur. | Event | Forecast | Previous |
| All Day | CNH | China - National Day | - | - |
| 14:30 | USD | Crude Oil Inventories | 1.900M | 0.922M |
| 17:00 | USD | 10-Year Note Auction | - | 4.384% |
| 18:00 | USD | FOMC Meeting Minutes | - | - |
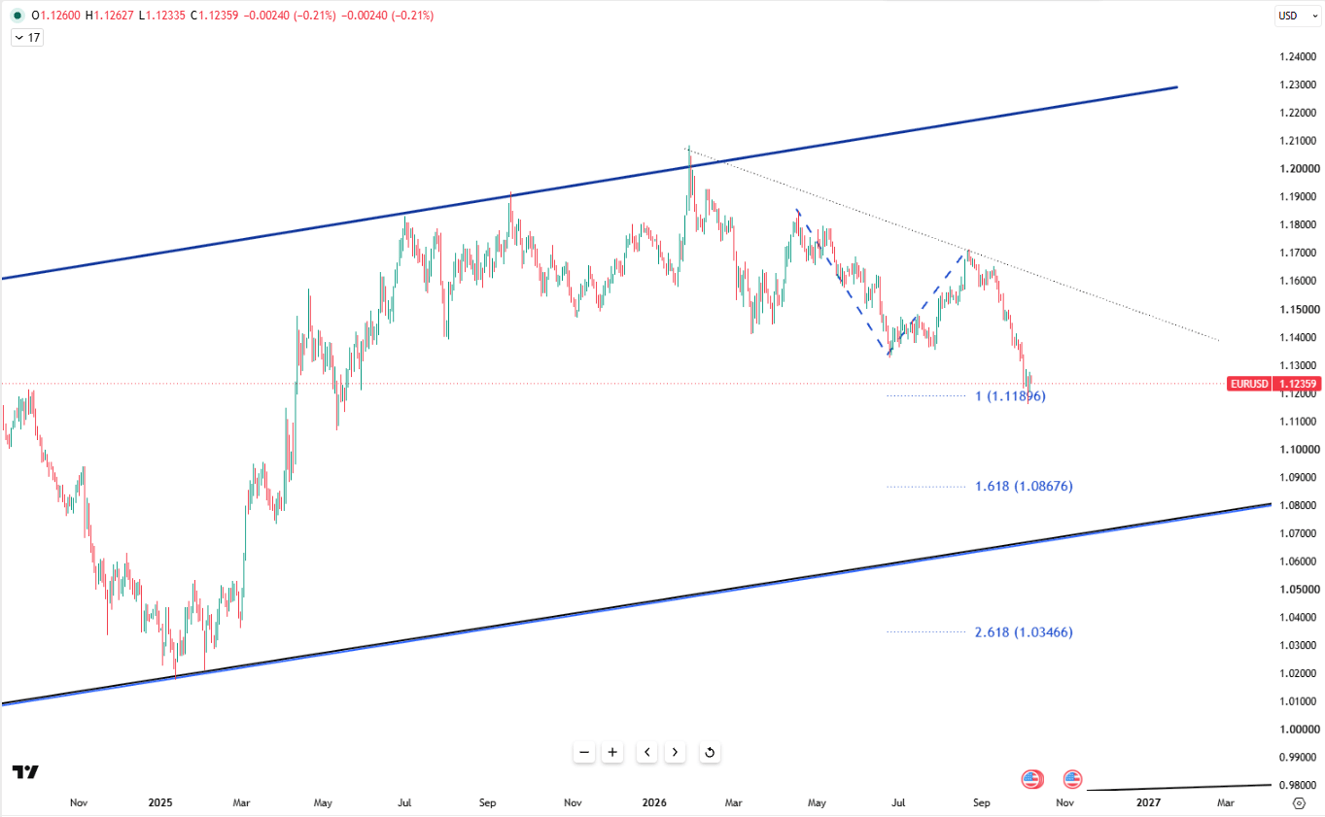
EUR/USD hovered around 1.1237 on Wednesday morning ahead of the FOMC minutes release, with markets pricing roughly a 78% probability of a Fed pause this month. European political and fiscal concerns, particularly French budget strains and elevated borrowing costs, kept euro gains limited, while the US 10-year yield holding at 5.29% provided ongoing support for the dollar.
The first resistance is positioned at 1.1260 while the support starts from 1.1190.
| R1: 1.1260 | S1: 1.1190 |
| R2: 1.1290 | S2: 1.1160 |
| R3: 1.1320 | S3: 1.1080 |
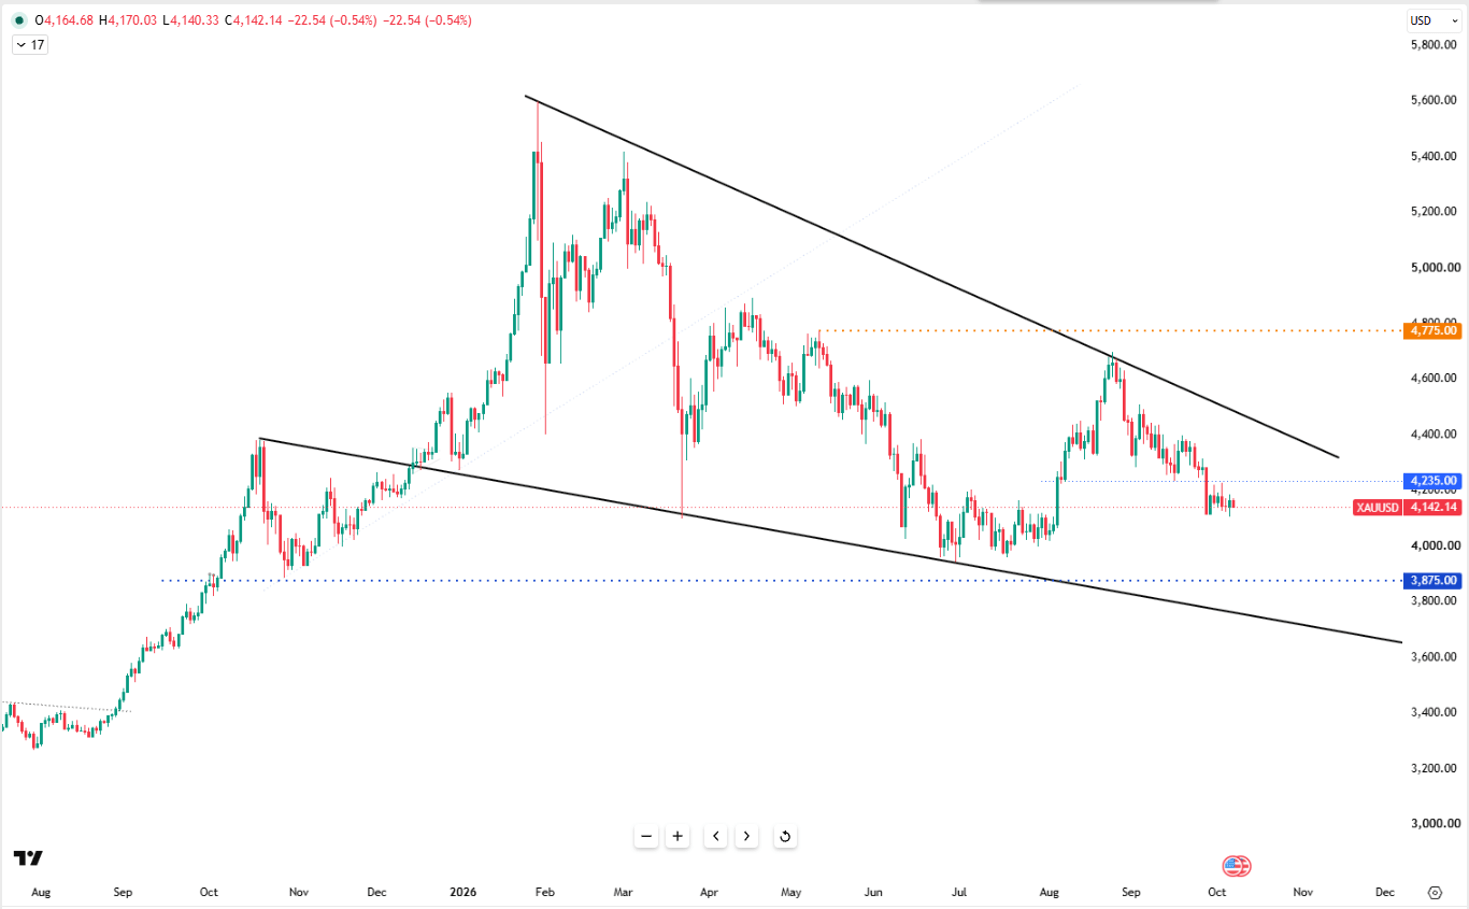
Gold slipped below $4,150 per ounce on Wednesday, surrendering part of Tuesday's gains as crude oil rebounded amid escalating Iranian tanker attacks in Hormuz and renewed Saudi-Houthi conflict. Re-ignited inflation and interest rate concerns kept Treasury yields near multi-decade highs, with markets pricing nearly an 80% chance of a Fed pause ahead of the FOMC minutes.
First resistance is seen at $4170, with initial support near $4100.
| R1: 4170 | S1: 4100 |
| R2: 4200 | S2: 4060 |
| R3: 4240 | S3: 4000 |
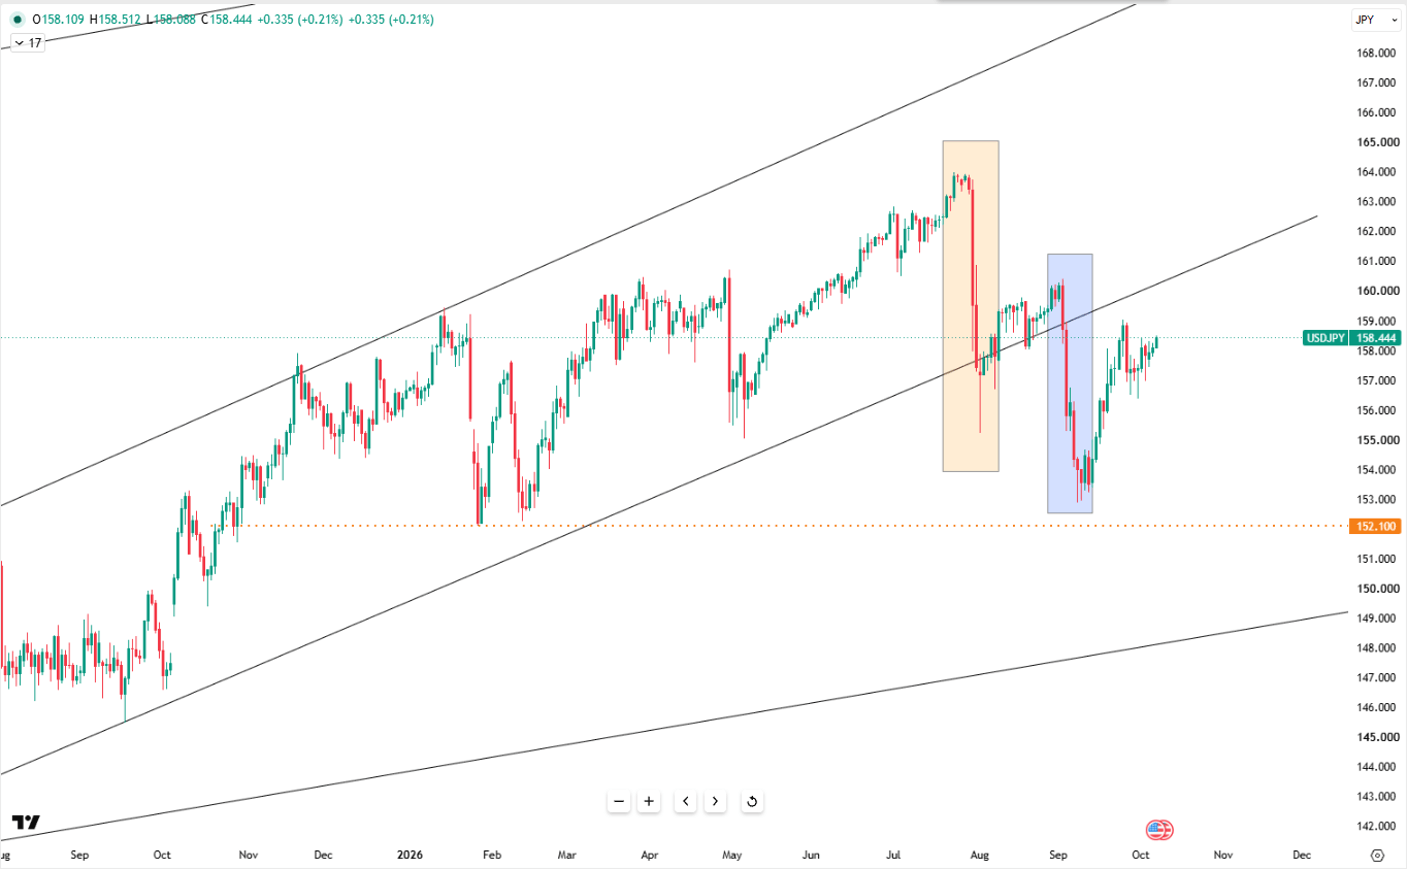
The yen slid toward 158.5 per dollar on Wednesday, nearing two-week lows as wide US-Japan yield differentials favored the dollar. Japanese rate levels, heavy public debt, and expansionary spending proposals under Takaichi added pressure. However, August real wages rose 1.5% for an eighth straight gain, while BoJ official Ayano Sato backed gradual monetary policy tightening.
First resistance is seen at 158.60, with initial support near 157.50.
| R1: 158.50 | S1: 157.50 |
| R2: 160.10 | S2: 155.40 |
| R3: 162.50 | S3: 152.60 |
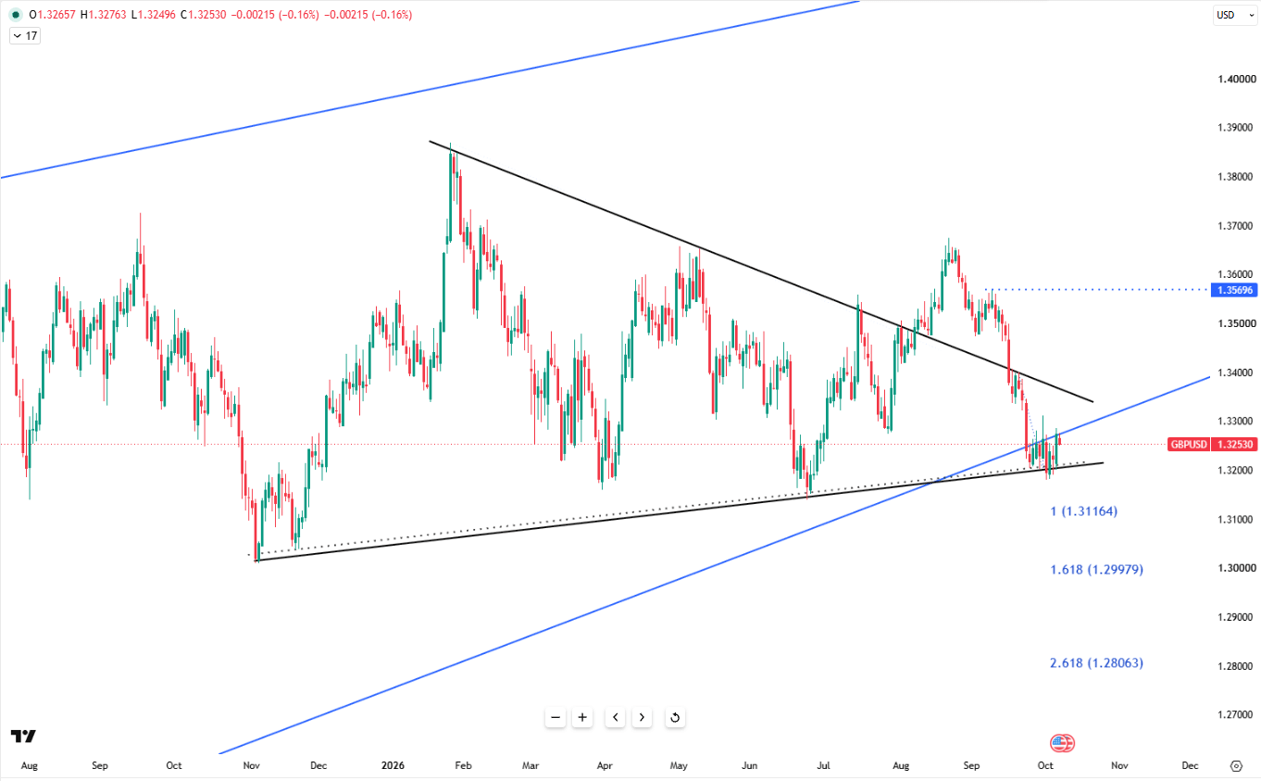
The British pound traded near $1.3248 on Wednesday, consolidating after a recovery from three-month lows as investors awaited Federal Reserve meeting minutes. Persistent UK inflation and elevated energy costs sustained Bank of England tightening expectations, offering underlying support. However, caution ahead of the late October UK Autumn Budget and a firm US dollar capped additional sterling upside.
From a technical view, resistance stands near 1.3340, with support around 1.3140.
| R1: 1.3340 | S1: 1.3140 |
| R2: 1.3350 | S2: 1.3100 |
| R3: 1.3400 | S3: 1.3050 |
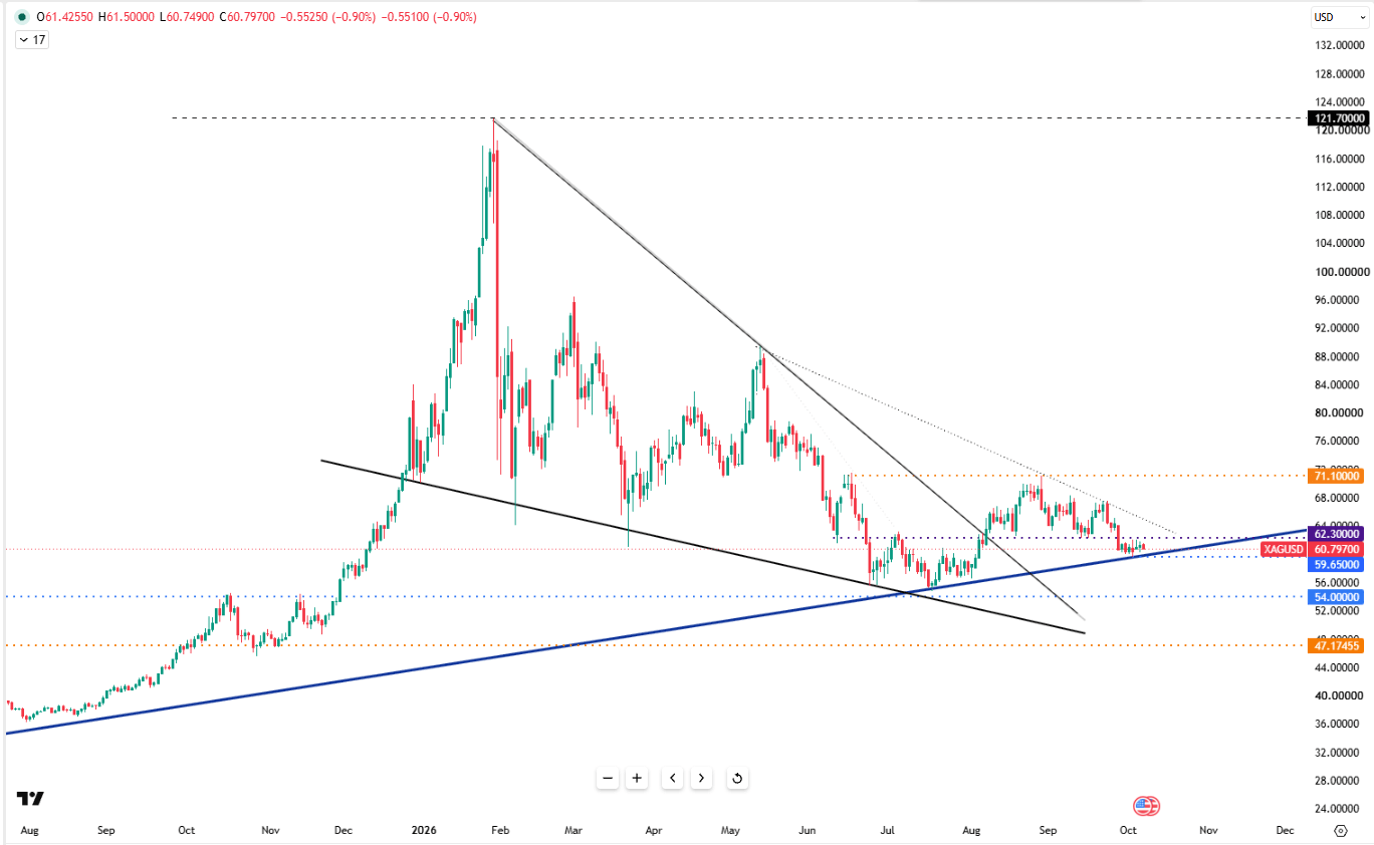
Silver fell below $61 per ounce on Wednesday, surrendering part of Tuesday's gains as crude oil rebounded following escalated Iranian tanker attacks in Hormuz and Saudi-Houthi clashes. The oil rally kept inflation and interest rate concerns at the forefront, holding Treasury yields near multi-decade highs while traders priced nearly an 80% probability of a Fed hold ahead of FOMC minutes.
From a technical view, resistance stands near $62.50, while support is located around $60.00.
| R1: 62.50 | S1: 60.00 |
| R2: 64.20 | S2: 59.60 |
| R3: 65.30 | S3: 57.50 |
The dollar index steadied around 102 on Tuesday, near its highest since April 2025, as the euro weakened on French fiscal and political concerns and Spain's upcoming snap election, yet stabilized near 1.1220 after touching its lowest level since May 2025.
Detail Weak US Jobs Ease Fed Hike Bets (5 – 9 October)
Weak US labor market data shifted the monetary policy outlook after September nonfarm payrolls rose by only 29,000, well below the 90,000 forecast, while prior months were revised lower. Unemployment rose to 4.2%, and wage growth slowed to 3.0%, cutting the probability of an October Fed hike to around 20%. The Dollar Index fell below 102 after the report, but remained on course for a third consecutive weekly gain.
DetailThen Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


