


Global markets opened the week with the dollar under pressure after unexpectedly weak U.S. employment data reduced expectations for a September Federal Reserve rate hike.
Gold and silver held onto strong gains, while the euro and sterling remained supported near recent highs. Meanwhile, the yen resumed its decline as wide rate differentials and higher energy costs outweighed the impact of recent intervention. Investors now turn to upcoming U.S. inflation data for further clues on the Fed’s policy path.
| Time | Cur. | Event | Forecast | Previous |
| All Day | SGD | Singapore – National Day (Holiday) | ||
| All Day | ZAR | South Africa – Women’s Day (Holiday) |
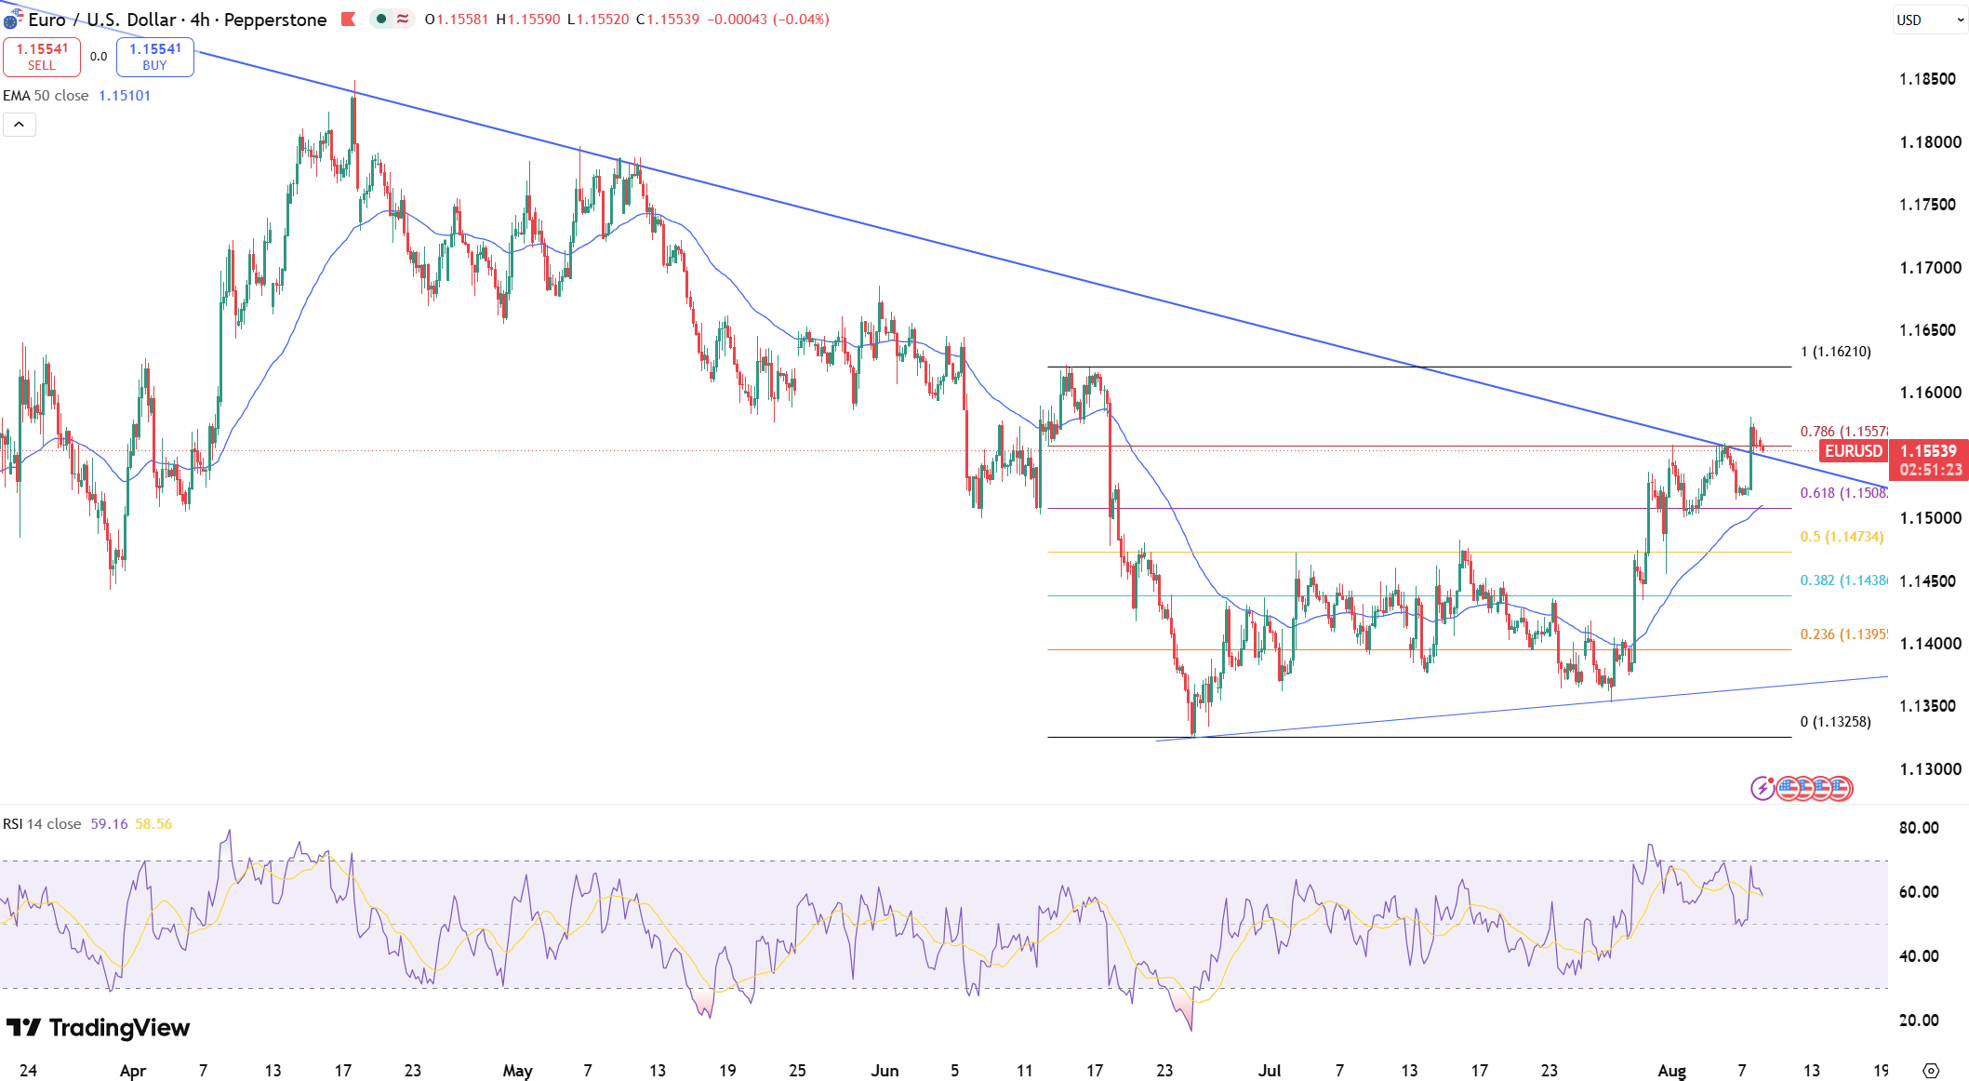
EUR/USD maintains a cautiously bullish stance below key resistance following recent multi-week highs. Weak US employment and services figures dragged the dollar lower, whereas steady Eurozone economic growth provided support despite the European Central Bank's pause. Mid East geopolitical tensions contribute to market volatility, leaving traders focused on upcoming US inflation data.
The first resistance is positioned at 1.1570 while the support starts from 1.1500.
| R1: 1.1570 | S1: 1.1500 |
| R2: 1.1590 | S2: 1.1470 |
| R3: 1.1610 | S3: 1.1420 |
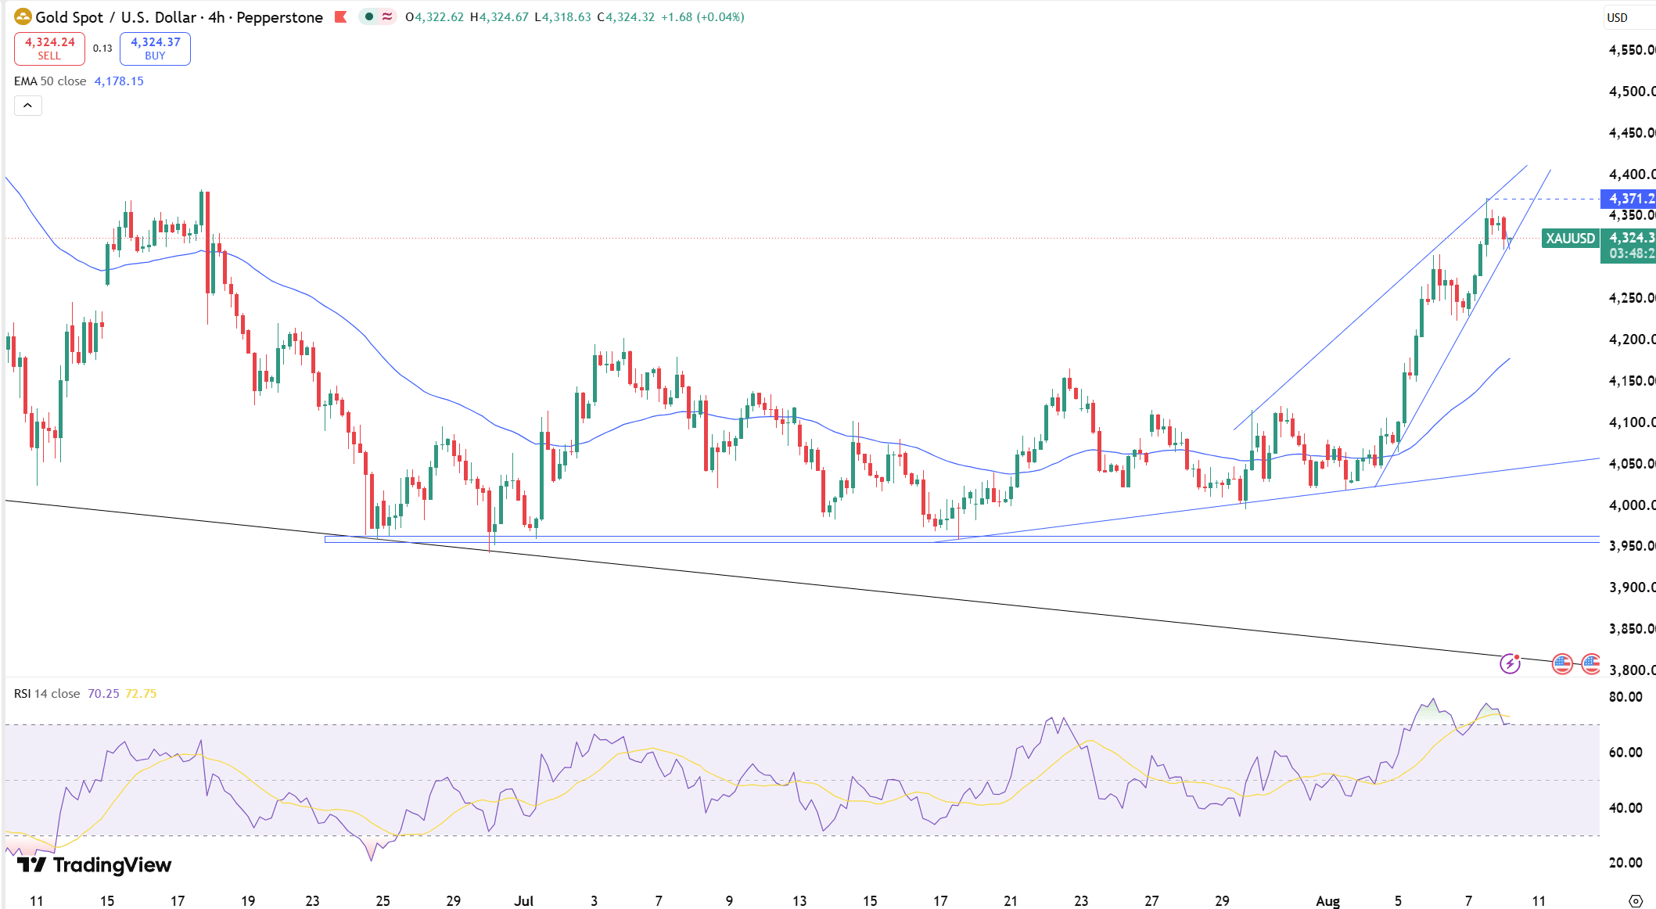
Gold maintained position above $4,300 on Monday, retaining last week's dramatic gains following an unexpected contraction in US payrolls. July employment dropped by 23,000, lowering September Fed rate hike expectations down to 44%. Metal prices remained resilient despite climbing oil valuations driven by Strait of Hormuz uncertainties and conflicting diplomatic statements regarding potential US-Iran negotiations.
First resistance is seen at $4350, with initial support near $4280.
| R1: 4350 | S1: 4280 |
| R2: 4400 | S2: 4200 |
| R3: 4490 | S3: 4150 |
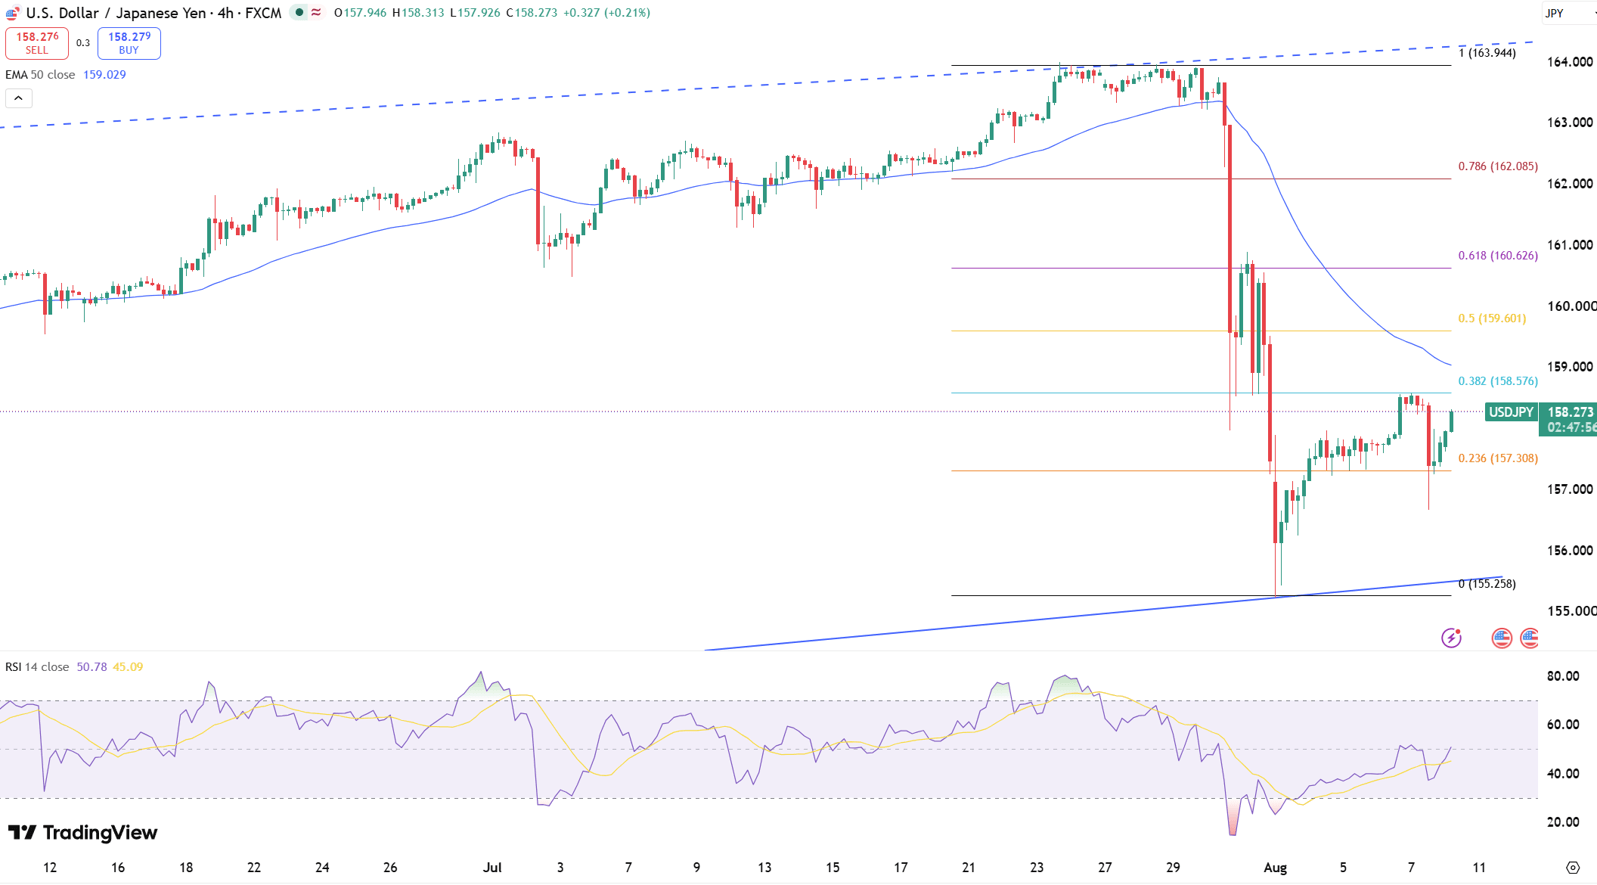
The Japanese yen dropped past 158 per dollar on Monday, erasing gains from recent joint market interventions by Tokyo and Washington. Wide interest rate gaps, fiscal worries, and high energy costs continue to exert significant pressure on the currency. Japan's narrowing current account surplus reflects rising oil import bills offsetting tech exports, even as Bank of Japan officials warn of inflation and hint at prospective rate hikes.
Initial resistance stands at 158.60, while the first support is at 157,30.
| R1: 158.60 | S1: 157.30 |
| R2: 160.00 | S2: 155.80 |
| R3: 162.10 | S3: 153.50 |
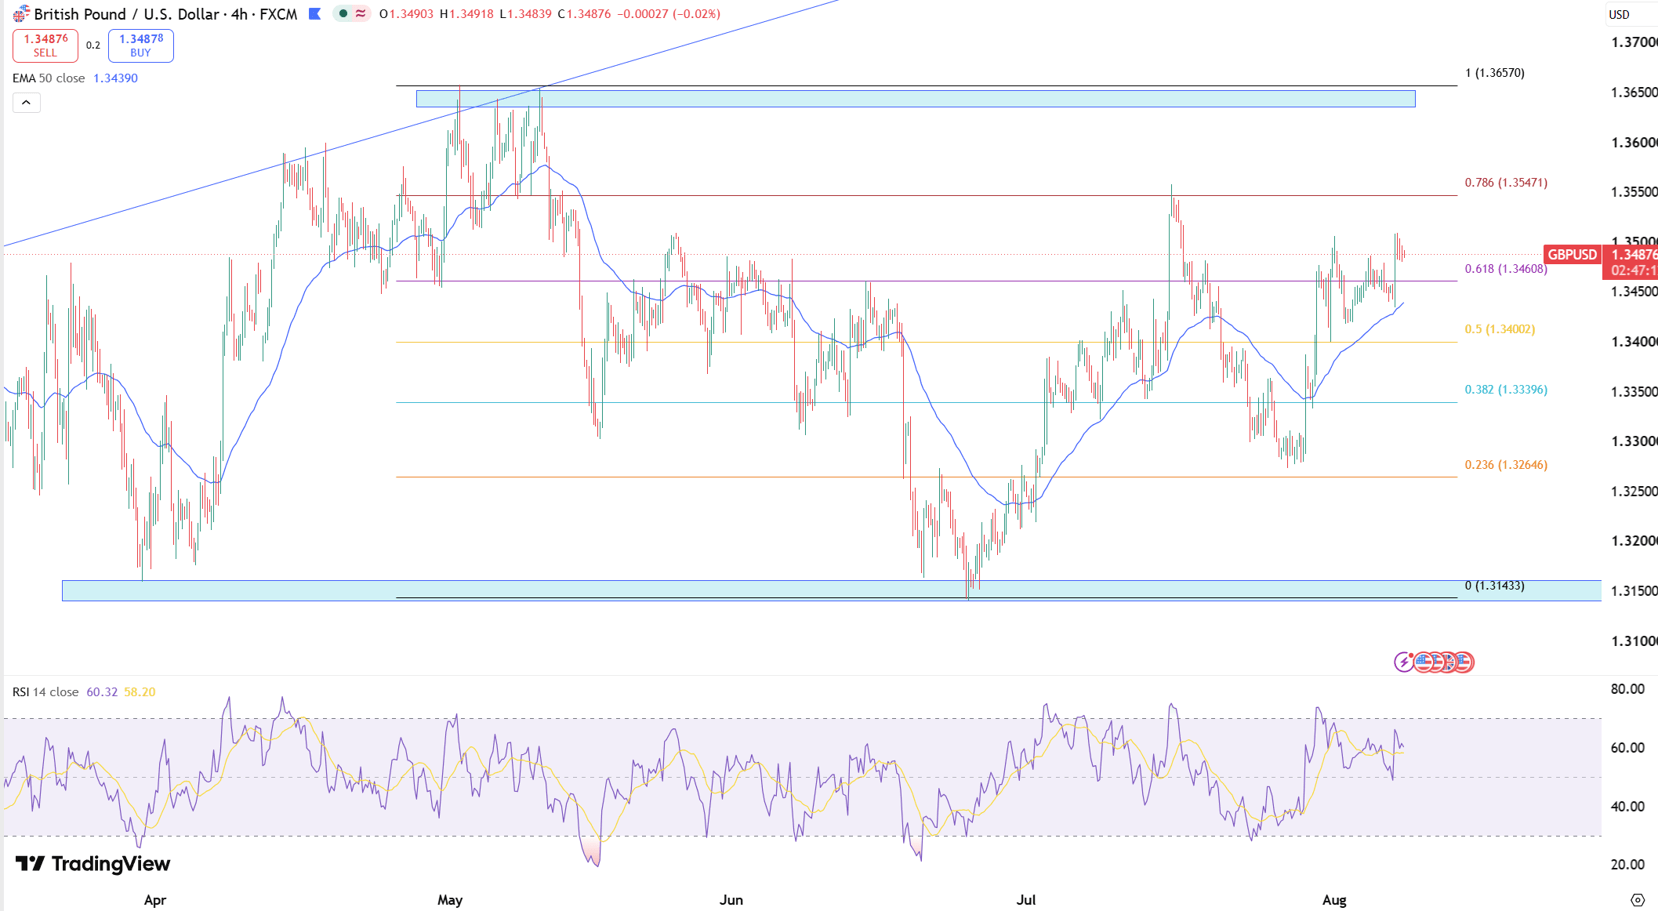
GBP/USD trades sideways near 1.3485, consolidating beneath key resistance at 1.3500. Disappointing US employment data keeps the dollar under pressure, while a close Bank of England decision to hold rates offers underlying support for Sterling. Although August historically favors sellers, bullish moving averages and healthy technical indicators keep momentum intact ahead of Wednesday's US inflation data.
From a technical view, resistance stands near 1.3500, with support around 1.3400.
| R1: 1.3500 | S1: 1.3400 |
| R2: 1.3540 | S2: 1.3320 |
| R3: 1.3600 | S3: 1.3240 |
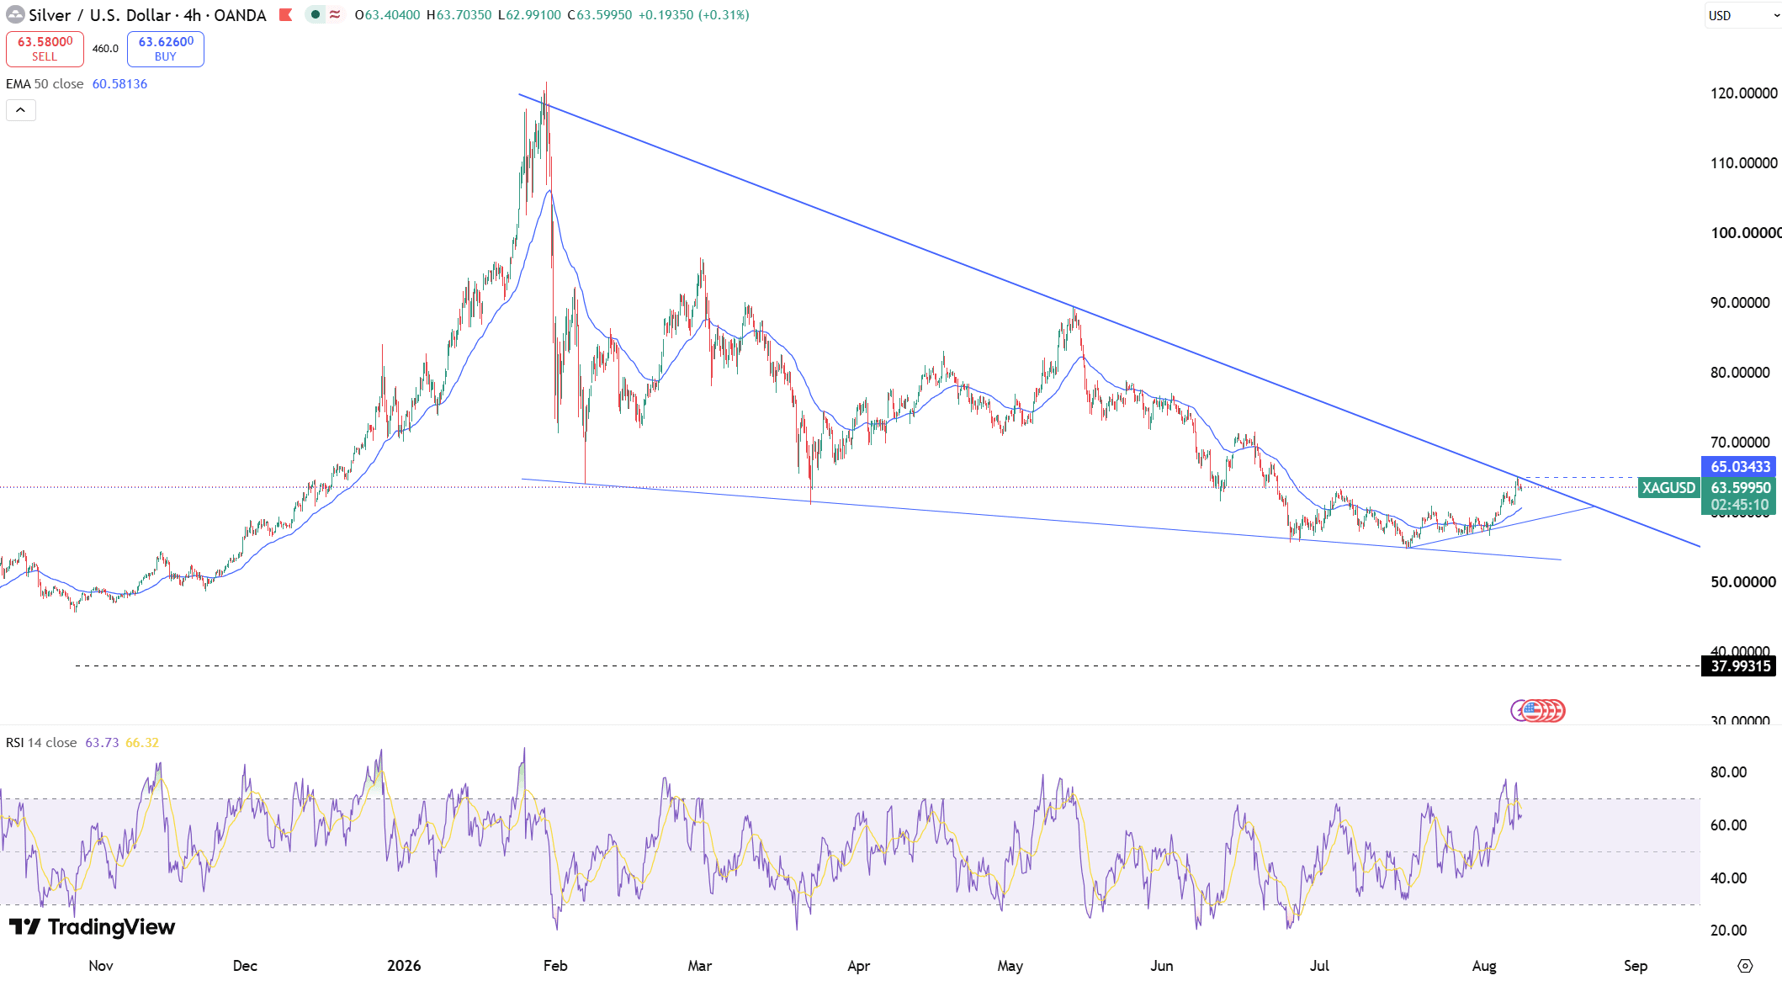
Silver traded around $64 per ounce on Monday, retaining last week's double-digit surge after an unexpected drop in US payrolls curbed Federal Reserve rate hike expectations. July employment shrank by 23,000, lowering September rate hike odds to 44%. Metal valuations remained resilient despite rising oil prices driven by Strait of Hormuz uncertainties and conflicting statements regarding potential US-Iran diplomatic progress.
From a technical view, resistance stands near $65.00, while support is located around $62.50.
| R1: 65.00 | S1: 62.50 |
| R2: 65.80 | S2: 61.20 |
| R3: 66.40 | S3: 60.00 |
Elevated oil prices and rising Treasury yields weighed on precious metals as persistent geopolitical tensions reinforced inflation concerns and expectations for further Federal Reserve tightening.
 European Daylight Saving Time (October 25, 2026)
We would like to inform you of upcoming adjustments to the trading schedule for selected instruments due to the end of Daylight Saving Time (DST) in Europe on October 25, 2026.
Detail Dollar Retreats as Safe-Haven Demand Rises (19 – 23 October)
Financial markets entered the week balancing persistent US inflation against growing concerns over equity valuations and artificial intelligence spending. The Dollar Index slipped to 101.6, recording its first weekly decline in four weeks, while safe-haven demand supported government bonds and precious metals. Despite stronger consumer and producer inflation, markets now assign an 85% probability to the Federal Reserve holding rates in October, with a 77% chance of another increase in December.
DetailThen Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


