

A firm US dollar and elevated Treasury yields continued to shape trading as September drew to a close.
The euro weakened toward 1.133 and sterling slipped near 1.32 as expectations for further Federal Reserve tightening outweighed policy support from the ECB and BoE. Gold stabilized around $4,180 and silver held above $61 as easing oil prices offered some relief, although both metals remained on track for steep monthly losses. Meanwhile, the yen strengthened past 157 following renewed warnings from Japanese officials over excessive currency movements.
| Time | Cur. | Event | Actual | Forecast | Previous |
| 01:30 | CNY | Manufacturing PMI (Sep) | 50.7 | 50.1 | 49.8 |
| 06:00 | GBP | GDP (QoQ) (Q2) | 0.5% | 0.4% | 0.6% |
| 06:00 | GBP | GDP (YoY) (Q2) | 1.4% | 1.2% | 0.9% |
| 12:15 | USD | ADP Nonfarm Employment Change (Sep) | 73K | 38K | |
| 12:30 | USD | Core PCE Price Index (YoY) (Aug) | 3.3% | 3.3% | |
| 12:30 | USD | Core PCE Price Index (MoM) (Aug) | 0.3% | 0.2% | |
| 12:30 | USD | GDP (QoQ) (Q2) | 1.5% | 2.1% | |
| 14:30 | USD | EIA Crude Oil Inventories | -0.700M | 2.969M |
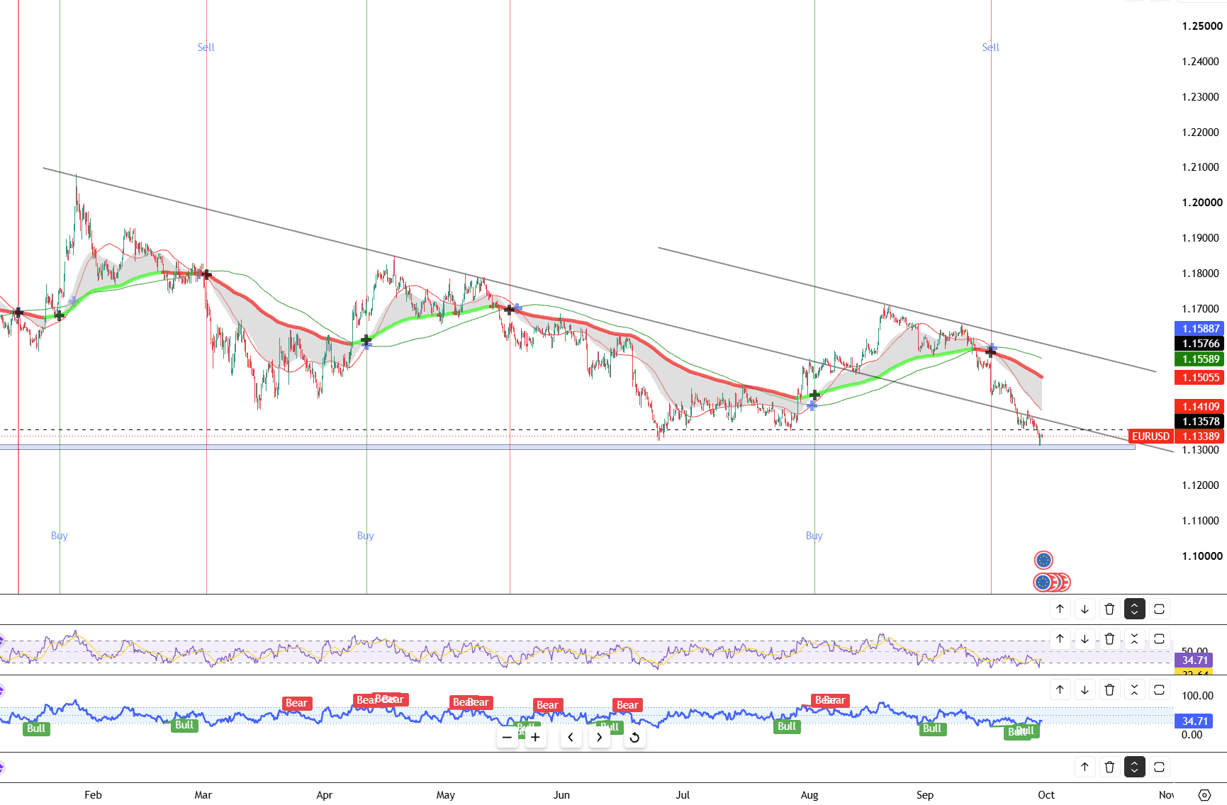
The euro fell to approximately $1.133, hitting its lowest level since May 2025, pressured by a strengthening US dollar and policy divergence expectations between central banks. Higher oil prices driven by stalled Hormuz negotiations have fueled bets on Federal Reserve tightening. Meanwhile, ECB President Christine Lagarde signaled a measured stance, noting limited second-round inflation effects. Despite sluggish European growth projections and upcoming political uncertainty, elevated inflation keeps four ECB rate hikes priced in over the coming year.
The first resistance is positioned at 1.1361 while the support starts from 1.1301.
| R1: 1.1361 | S1: 1.1301 |
| R2: 1.1400 | S2: 1.1280 |
| R3: 1.1450 | S3: 1.1260 |
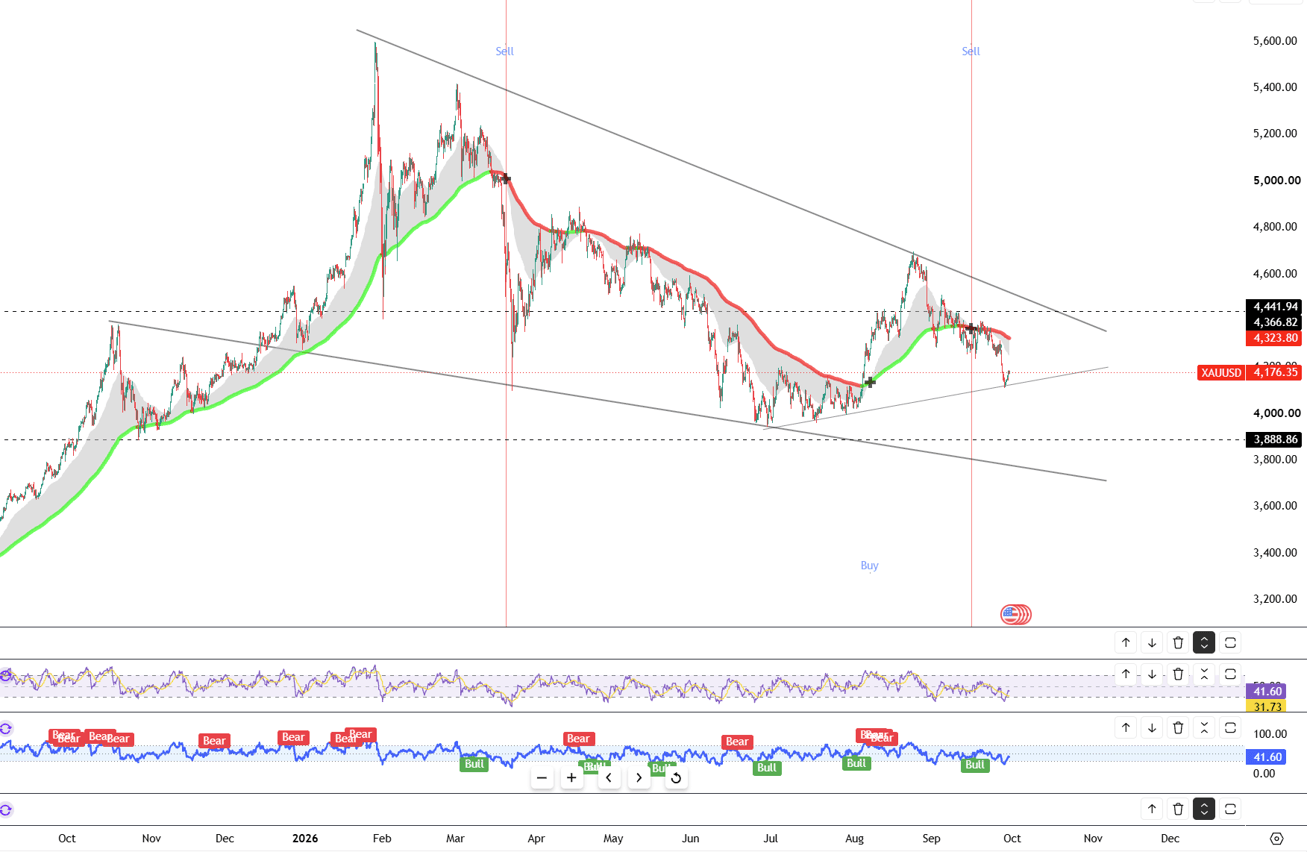
Gold stabilized near $4,180 per ounce following a previous session rebound, drawing support from easing crude oil prices. Upside remains constrained by elevated Treasury yields, with the 30-year rate hitting 5.62%, its highest level since June 2002. Persistent inflation concerns and hawkish Federal Reserve rhetoric continue to weigh on non-yielding assets, with New York Fed President John Williams suggesting a potential late-year rate hike. Gold remains set for a nearly 6% decline in September.
First resistance is seen at $4230, with initial support near $4140.
| R1: 4230 | S1: 4140 |
| R2: 4290 | S2: 4110 |
| R3: 4320 | S3: 4080 |
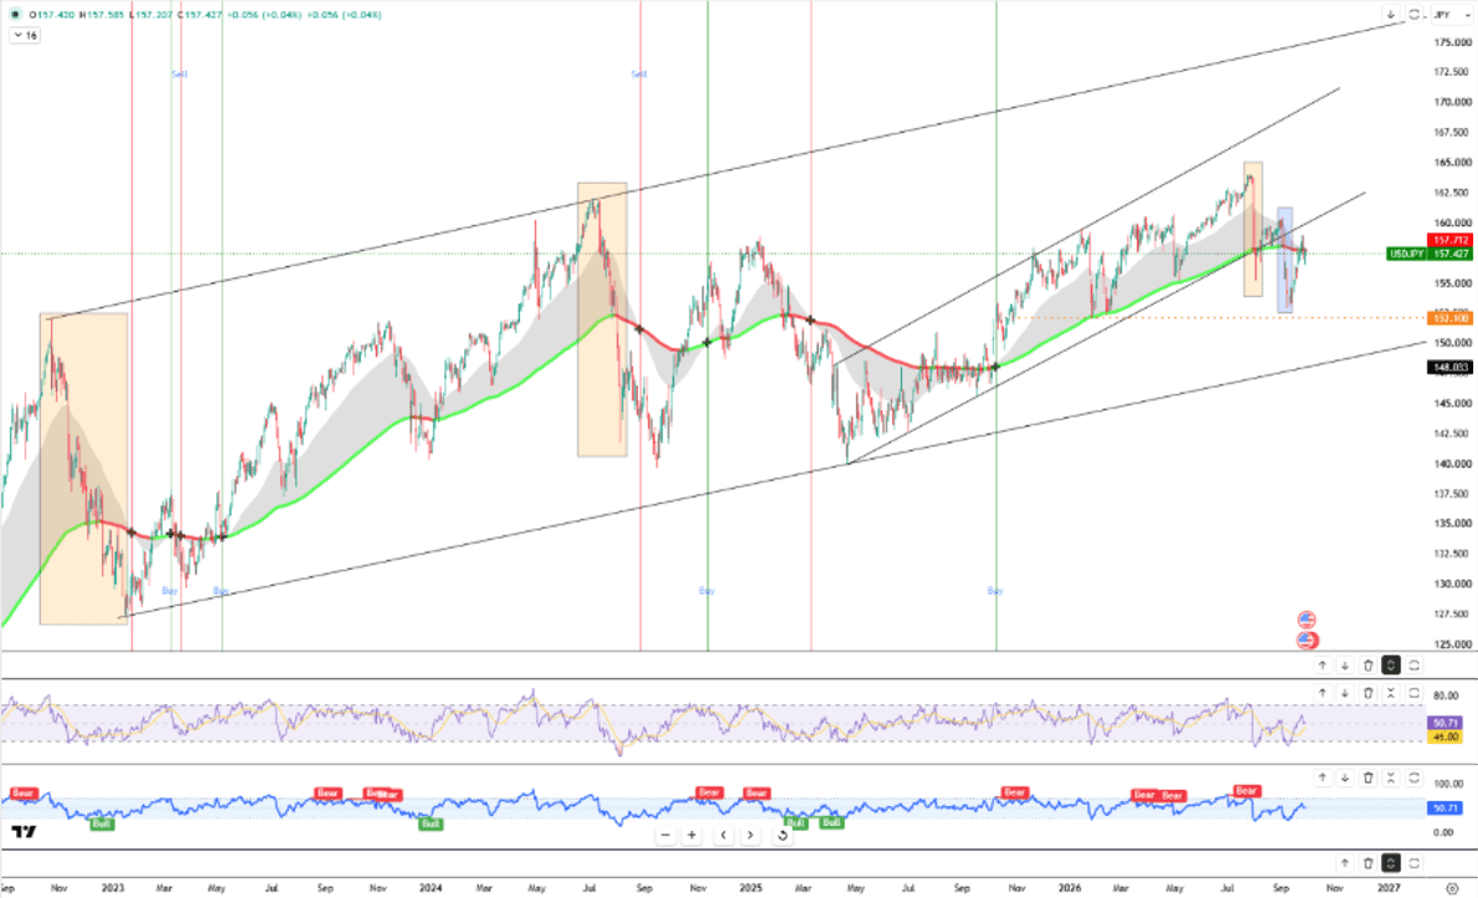
Japanese officials warned against rapid currency movements and confirmed joint coordination with the United States, helping the yen firm past 157 per dollar. Nevertheless, substantial interest rate differentials between the US and Japan continue to exert persistent downward pressure on the currency.
First resistance is seen at 159.50, with initial support near 155.00.
| R1: 159.50 | S1: 155.00 |
| R2: 161.10 | S2: 153.40 |
| R3: 165.50 | S3: 152.60 |
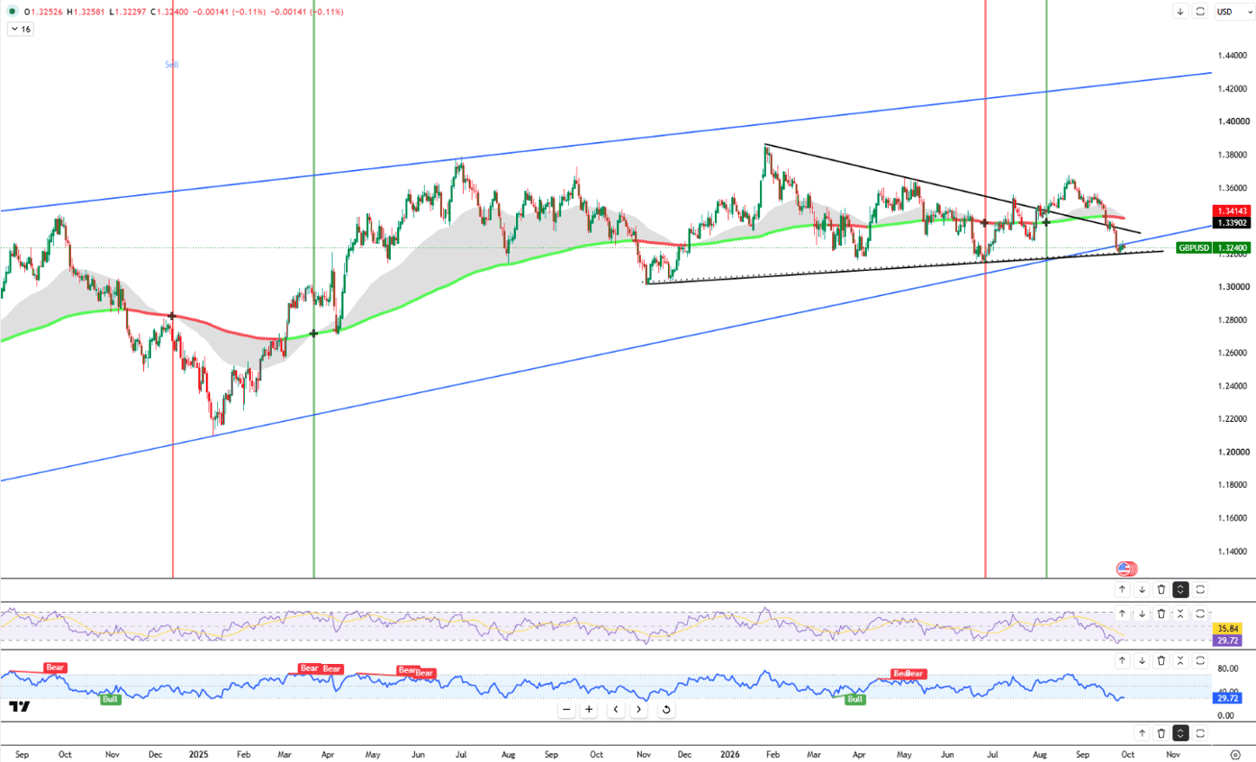
Sterling fell toward $1.32, hovering near a three-month low, as expectations build for an October Federal Reserve interest rate hike while the Bank of England is projected to wait until November. Although markets price an 80% chance of a November BoE increase from its current 3.75% rate, sluggish UK economic growth may restrict additional monetary tightening.
From a technical view, resistance stands near 1.3260, with support around 1.3200.
| R1: 1.3260 | S1: 1.3200 |
| R2: 1.3300 | S2: 1.3170 |
| R3: 1.3350 | S3: 1.3100 |
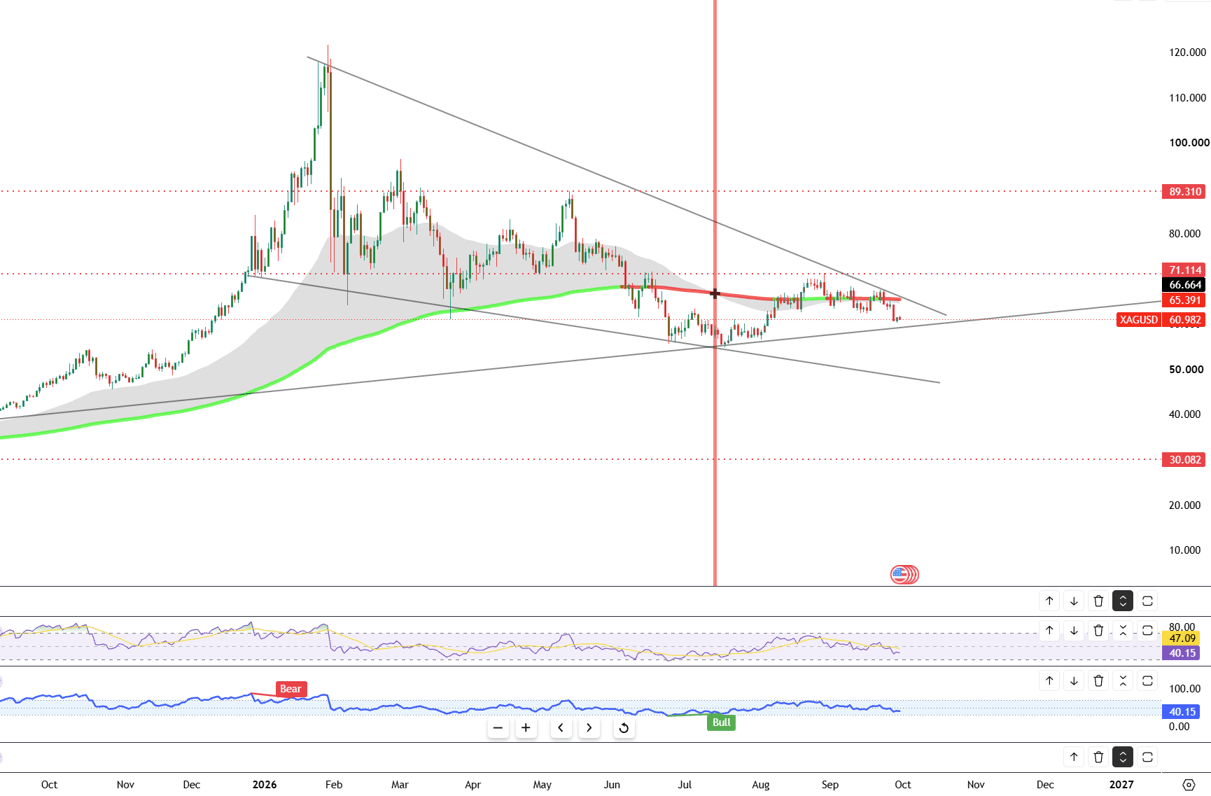
Silver stabilized above $61 per ounce, snapping its recent slide as easing crude oil prices provided underlying support. However, high Treasury yields and hawkish Federal Reserve commentary continue to create strong headwinds, leaving the metal on track for a nearly 8% monthly decline.
From a technical view, resistance stands near $62.70, while support is located around $59.60.
| R1: 62.70 | S1: 59.60 |
| R2: 63.20 | S2: 59.00 |
| R3: 64.30 | S3: 58.50 |
Elevated Treasury yields and persistent expectations for further Federal Reserve tightening continued to shape market sentiment.
Detail Fed Hike Bets and Hormuz Tensions Lift Markets (28 September – 2 October)
The week started with renewed pressure from rising oil prices and expectations for further monetary tightening. The Dollar Index climbed toward 101.1, near a two-month high, as several Federal Reserve officials cited resilient economic growth, a strong labor market, and persistent inflation risks as reasons to hike rates further. Markets now price in roughly a 66% chance of another Fed hike in October, while the US 10-year Treasury yield has climbed to its highest level since 2007.
DetailThen Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


