

This week, the attention shifted toward Wednesday’s Federal Reserve decision as persistent inflation and surging energy costs strengthened expectations for another rate hike.
EUR/USD remained locked near 1.1590 despite the ECB’s latest 25-basis-point increase, while sterling struggled near 1.3520 as dollar demand offset stronger UK growth. Gold stayed under pressure around $4,300 and silver traded near $63.5 as higher rates and energy costs weighed on precious metals. The yen also weakened beyond 154, although elevated Japanese producer inflation kept expectations for a Bank of Japan rate hike alive.
| Time | Cur. | Event | Forecast | Previous |
| 09:15 | EUR | ECB's Schnabel Speaks | ||
| 15:15 | EUR | ECB President Lagarde Speaks |
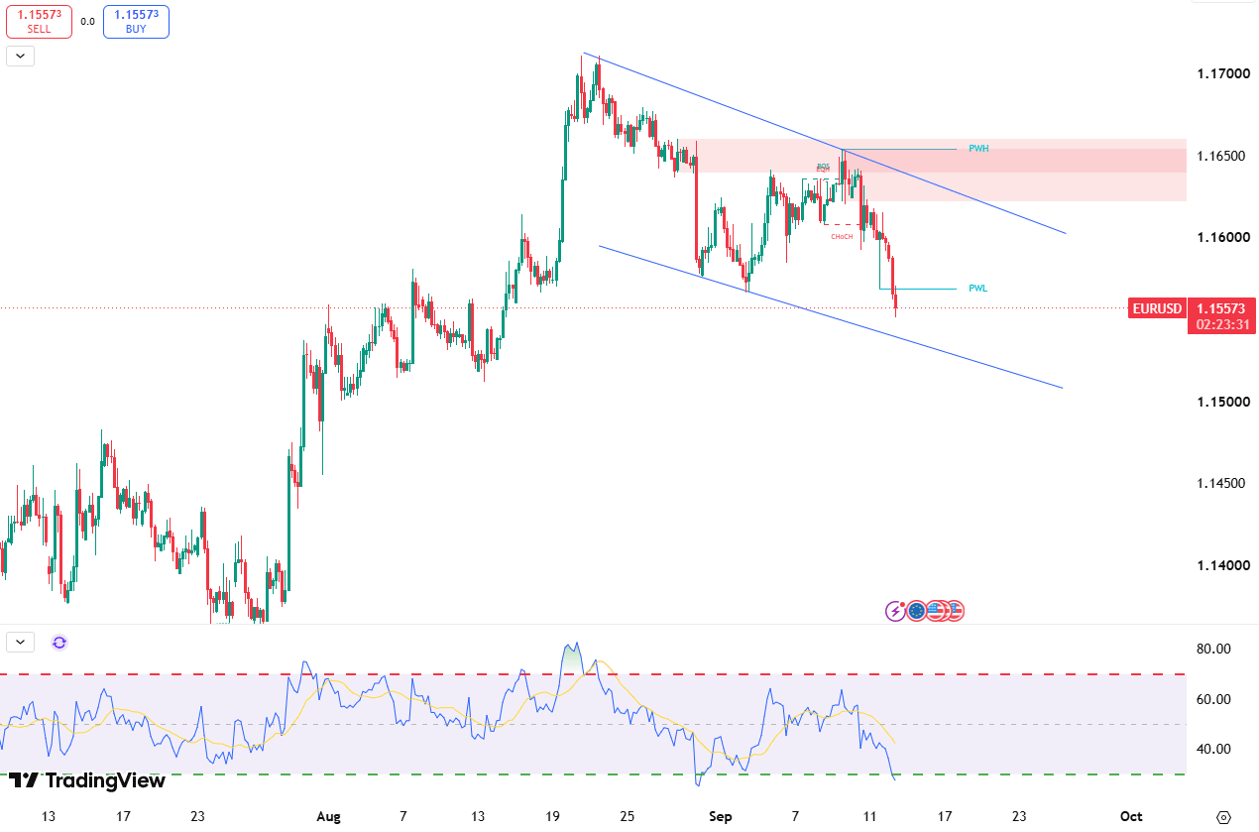
The EUR/USD pair remained range-bound near 1.1590 for a third straight week, constrained within a tight 100-pip corridor as traders awaited Wednesday's Federal Reserve policy decision. Meanwhile, the European Central Bank delivered an expected 25 basis point rate increase, raising the deposit rate to 2.50%. ECB President Christine Lagarde maintained a hawkish tone in subsequent comments, though her remarks aligned closely with existing market expectations.
The first resistance is positioned at 1.1640 while the support starts from 1.1560.
| R1: 1.1640 | S1: 1.1560 |
| R2: 1.1680 | S2: 1.1530 |
| R3: 1.1710 | S3: 1.1500 |
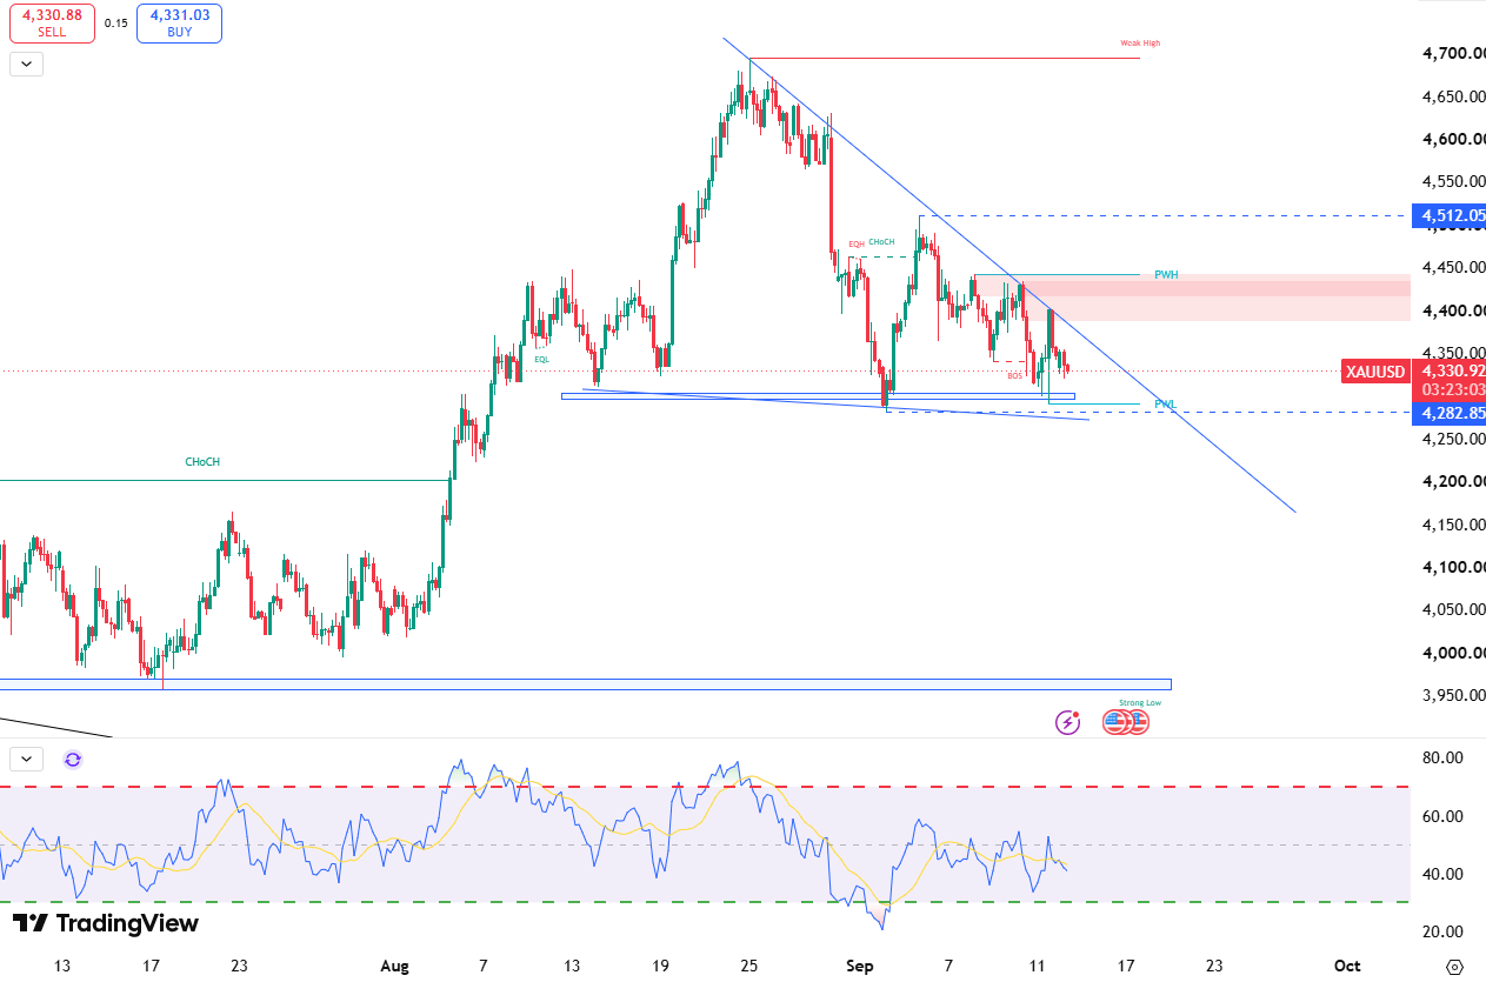
Gold remained under pressure around $4,300 per ounce on Monday after three consecutive weeks of declines. Surging energy prices, triggered by Saudi Arabia closing a vital pipeline following drone strikes, expanded inflationary concerns and reinforced expectations of Federal Reserve monetary tightening. Markets now price in an 86% probability of a 25 basis point rate hike on Wednesday, following August US CPI data showing annual inflation held at 3.4% with monthly prices advancing 0.4%.
First resistance is seen at $4350, with initial support near $4260.
| R1: 4350 | S1: 4260 |
| R2: 4400 | S2: 4200 |
| R3: 4470 | S3: 4140 |
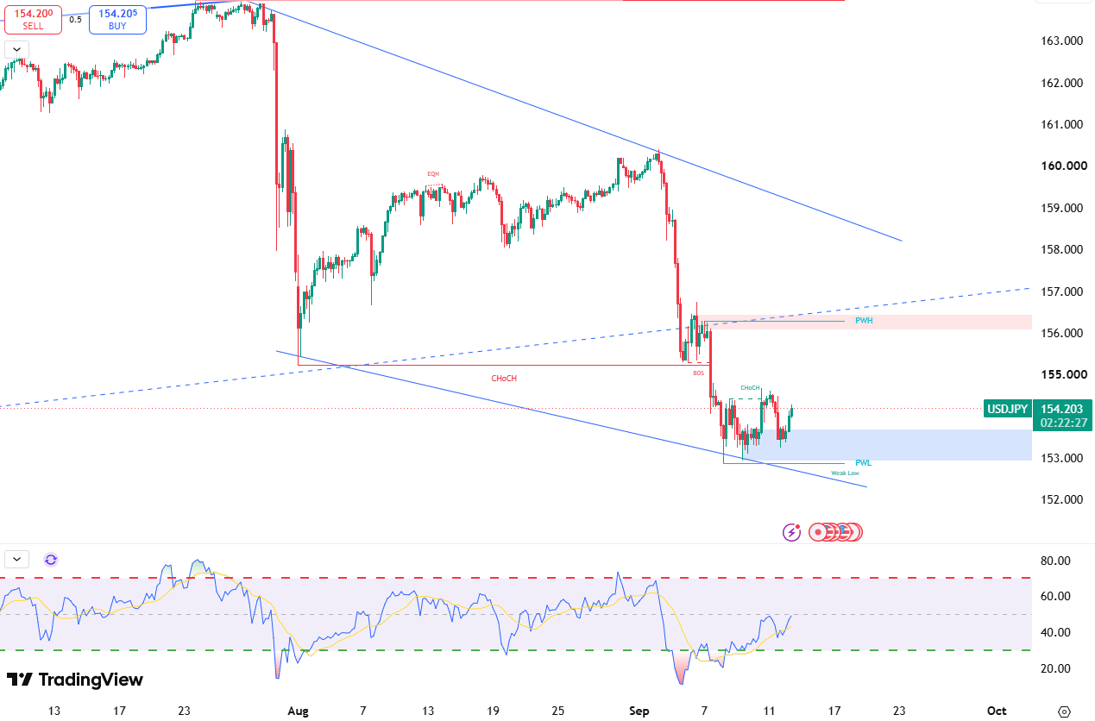
The Japanese yen slipped past 154 per dollar on Monday, backing off from near seven-month peaks as a recovering US dollar gained momentum from accelerated August producer inflation data, supporting Federal Reserve rate hike bets. Higher oil prices and the ongoing US-Iran conflict added further pressure. However, Japanese producer inflation rose 7.6% in August, maintaining market expectations for a potential Bank of Japan interest rate increase this month.
First resistance is seen at 155.00, with initial support near 153.80.
| R1: 155.00 | S1: 153.80 |
| R2: 156.00 | S2: 151.50 |
| R3: 157.20 | S3: 150.00 |
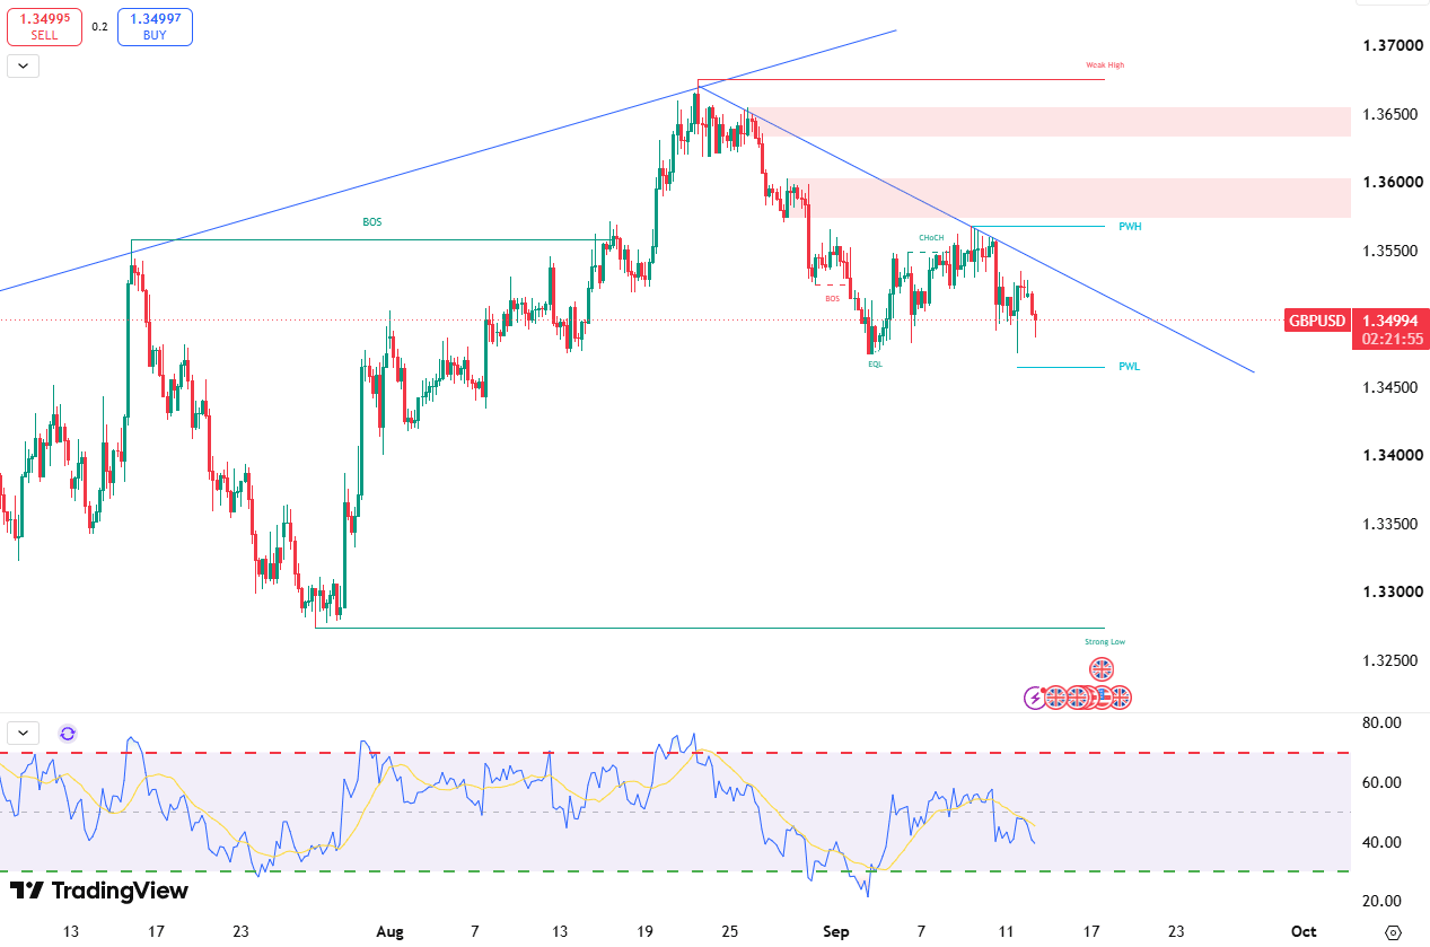
The GBP/USD pair struggled to hold modest early gains on Monday, consolidating around the 1.3520 level while staying above weekly lows. Sterling drew initial support from surprisingly strong UK GDP data, which revealed 0.4% economic expansion in July against forecasts of flat growth. However, hotter US producer price figures reinforced expectations of Federal Reserve monetary tightening. Persistent geopolitical risks spurred demand for the safe-haven dollar, capping potential upside for the pound.
From a technical view, resistance stands near 1.3530, with support around 1.3450.
| R1: 1.3530 | S1: 1.3450 |
| R2: 1.3570 | S2: 1.3420 |
| R3: 1.3600 | S3: 1.3400 |
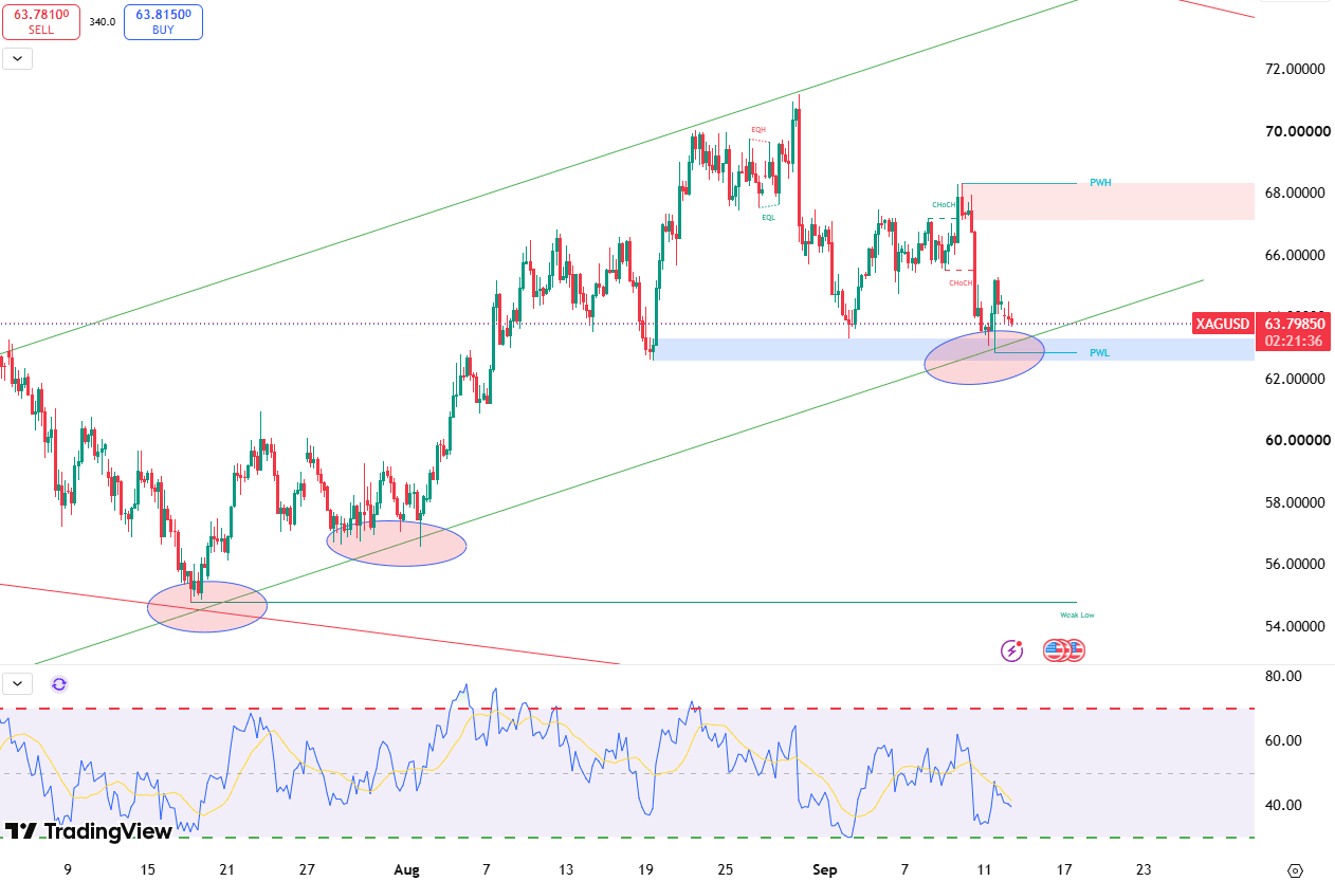
Silver traded near $63.5 per ounce after dropping more than 5% on Thursday, as market participants awaited key CPI figures. Higher producer price data previously pushed Fed rate hike probabilities to 71%. Surging oil costs tied to the US-Iran conflict and climbing Treasury yields added further pressure, leaving silver on path for a third consecutive weekly decline.
From a technical view, resistance stands near $64.80, while support is located around $62,70.
| R1: 64.80 | S1: 62.70 |
| R2: 66.50 | S2: 61.50 |
| R3: 68.00 | S3: 60.00 |
The dollar index steadied around 102 on Tuesday, near its highest since April 2025, as the euro weakened on French fiscal and political concerns and Spain's upcoming snap election, yet stabilized near 1.1220 after touching its lowest level since May 2025.
Detail Weak US Jobs Ease Fed Hike Bets (5 – 9 October)
Weak US labor market data shifted the monetary policy outlook after September nonfarm payrolls rose by only 29,000, well below the 90,000 forecast, while prior months were revised lower. Unemployment rose to 4.2%, and wage growth slowed to 3.0%, cutting the probability of an October Fed hike to around 20%. The Dollar Index fell below 102 after the report, but remained on course for a third consecutive weekly gain.
Detail Safe-Haven Demand Keeps Dollar Firm (10.05.2026)Safe-haven demand and elevated Treasury yields supported the dollar as Middle East tensions kept investors cautious at the start of the week.
Then Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


