

Hawkish Federal Reserve meeting minutes reinforced expectations for another rate hike this year, pushing Treasury yields higher and supporting the US dollar.
The dollar index remained above 102 on Thursday, close to its highest since April 2025, as hawkish FOMC minutes showed all 19 policymakers supported September's increase, with most expecting another before year-end. Gold remained near two-month lows around $4,120, while silver slipped below $60 as rising oil prices renewed inflation concerns amid escalating US-Iran tensions. The euro struggled near 1.1205 amid European fiscal and economic uncertainty, while sterling consolidated around 1.3212 as UK stagflation risks increased. Meanwhile, the yen held near 158 despite stronger Japanese current account figures, with wide US-Japan yield differentials continuing to limit its recovery.
| Time | Cur. | Event | Forecast | Previous |
| 12:30 | USD | Initial Jobless Claims | 200K | 197K |
| 17:00 | USD | 30-Year Bond Auction | - | 5.308% |
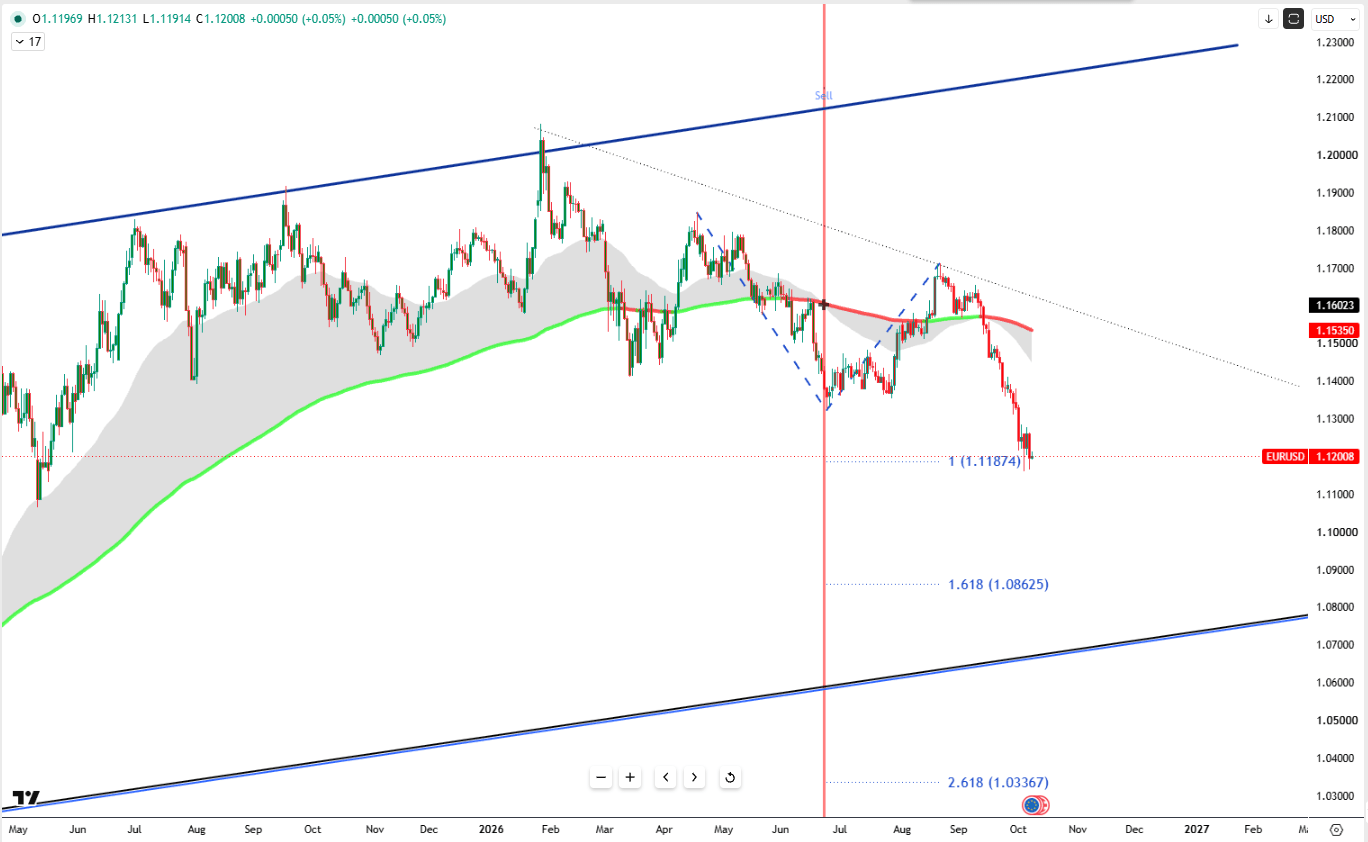
EUR/USD traded near 1.1205 on Thursday, attempting to stabilize following a drop to 1.1162, its lowest point in 17 months. Eurozone sentiment remains weighed down by French debt concerns, Spain's snap election, and a 10.6% plunge in German factory orders. U.S. 10-year Treasury yields topping 5.3% widened rate differentials ahead of upcoming U.S. jobless claims data.
The first resistance is positioned at 1.1250 while the support starts from 1.1180.
| R1: 1.1250 | S1: 1.1180 |
| R2: 1.1290 | S2: 1.1140 |
| R3: 1.1320 | S3: 1.1080 |
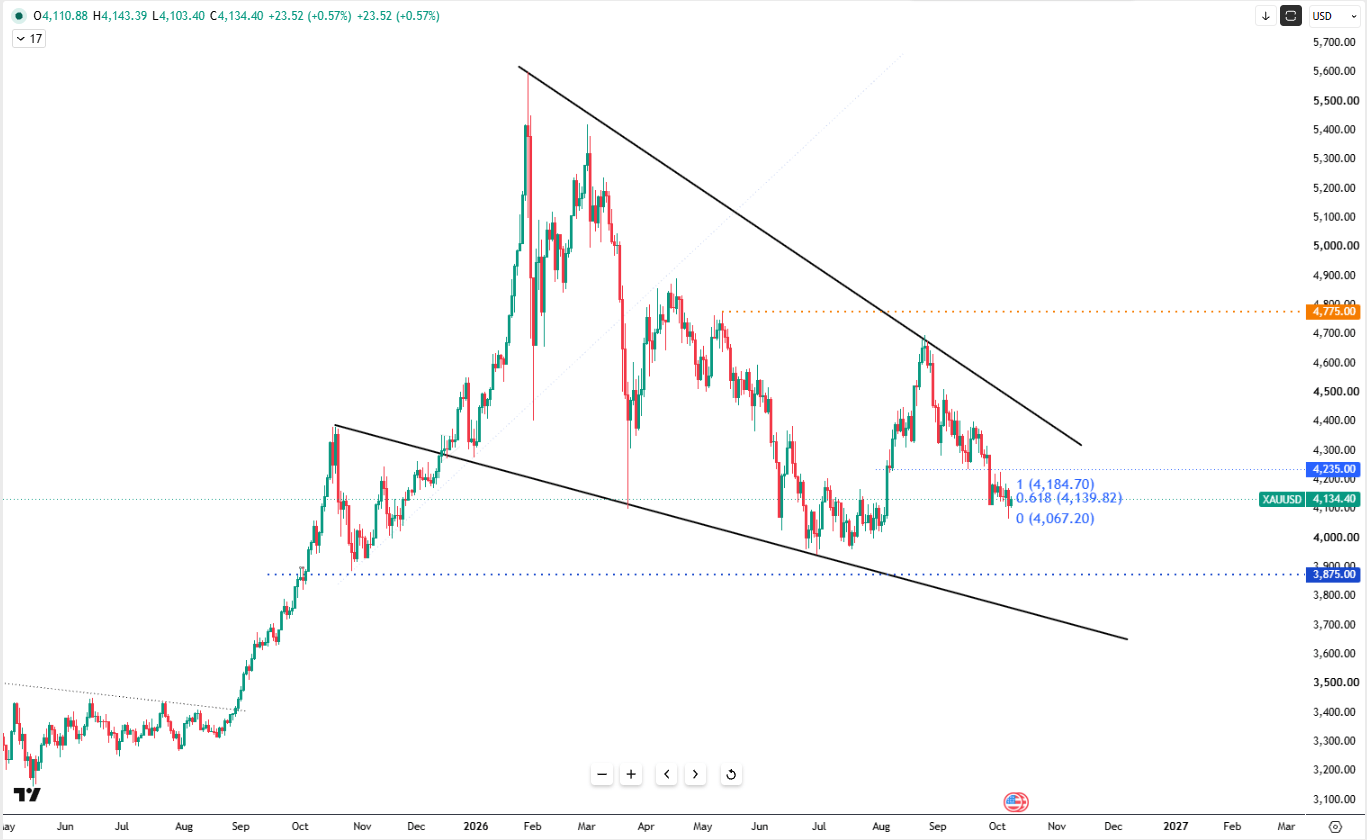
Gold hovered near $4,120 per ounce on Thursday, remaining suppressed around multi-month lows as hawkish FOMC minutes signaled heightened probability of another U.S. interest rate hike this year. Markets currently price a 78% chance of a December move. Meanwhile, oil prices advanced following reports of Washington seeking strike plans against Iran before the midterms, re-igniting energy-driven inflation fears.
First resistance is seen at $4155, with initial support near $4100.
| R1: 4155 | S1: 4100 |
| R2: 4200 | S2: 4060 |
| R3: 4240 | S3: 4000 |
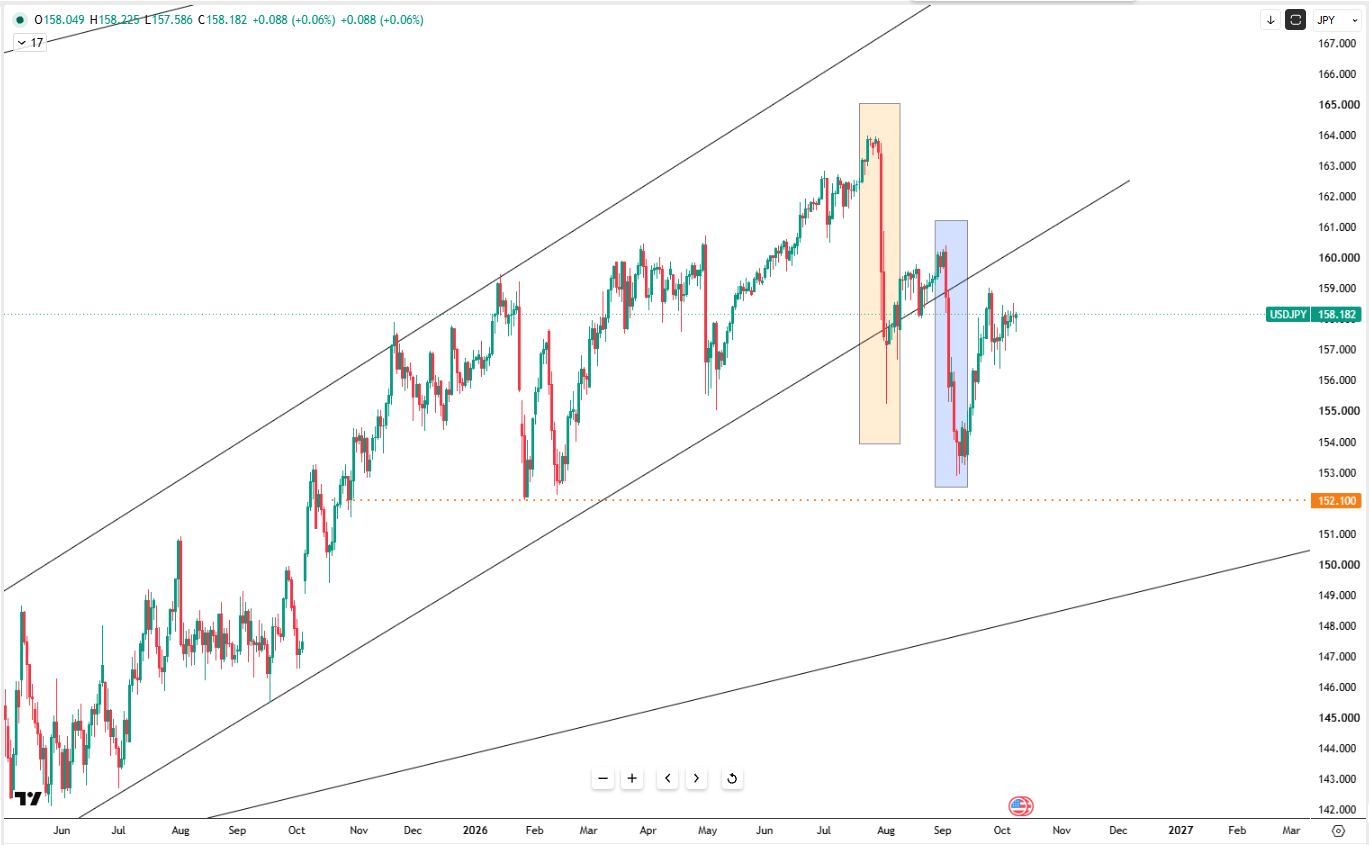
The Japanese Yen traded mostly flat near 158 per dollar on Thursday. A surging August current account surplus of ¥4.062 trillion surpassed expectations, providing underlying support. However, wide U.S.-Japan yield spreads, domestic fiscal expansion under Takaichi, and heavy public debt continue to weigh on the currency, while BoJ member Ayano Sato advocated for measured, staged rate adjustments.
First resistance is seen at 158.60, with initial support near 157.50.
| R1: 158.60 | S1: 157.50 |
| R2: 160.10 | S2: 155.40 |
| R3: 162.50 | S3: 152.60 |
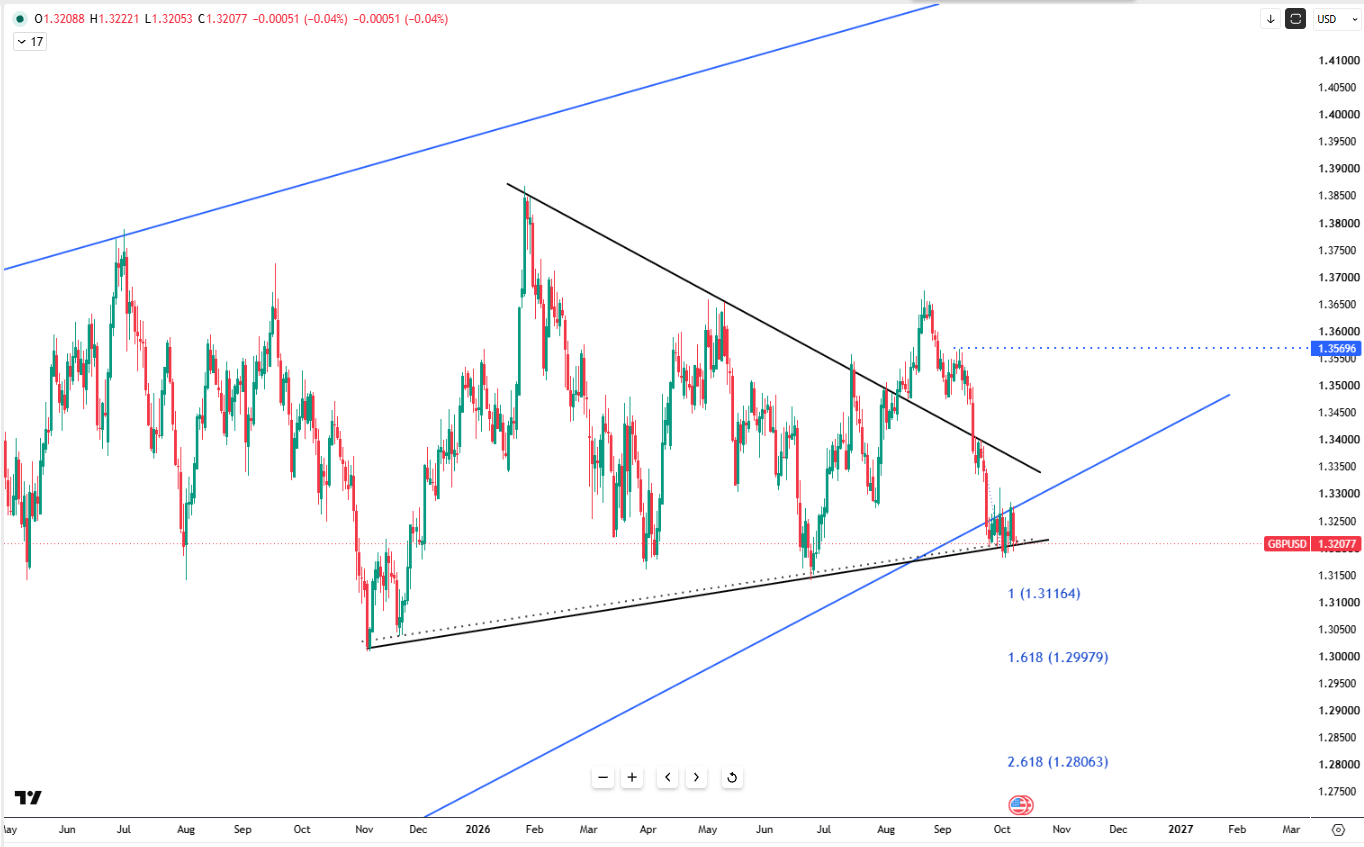
The British Pound traded near $1.3212 on Thursday, consolidating as strong U.S. Dollar demand maintained pressure on sterling. A surge in U.S. 10-year Treasury yields past 5.35% diverted capital from risk-sensitive currencies. Meanwhile, growing UK stagflation fears driven by high energy costs and borrowing rates kept buyers sidelined ahead of U.S. jobless claims.
From a technical view, resistance stands near 1.3250, with support around 1.3160.
| R1: 1.3250 | S1: 1.3160 |
| R2: 1.3320 | S2: 1.3100 |
| R3: 1.3400 | S3: 1.3050 |
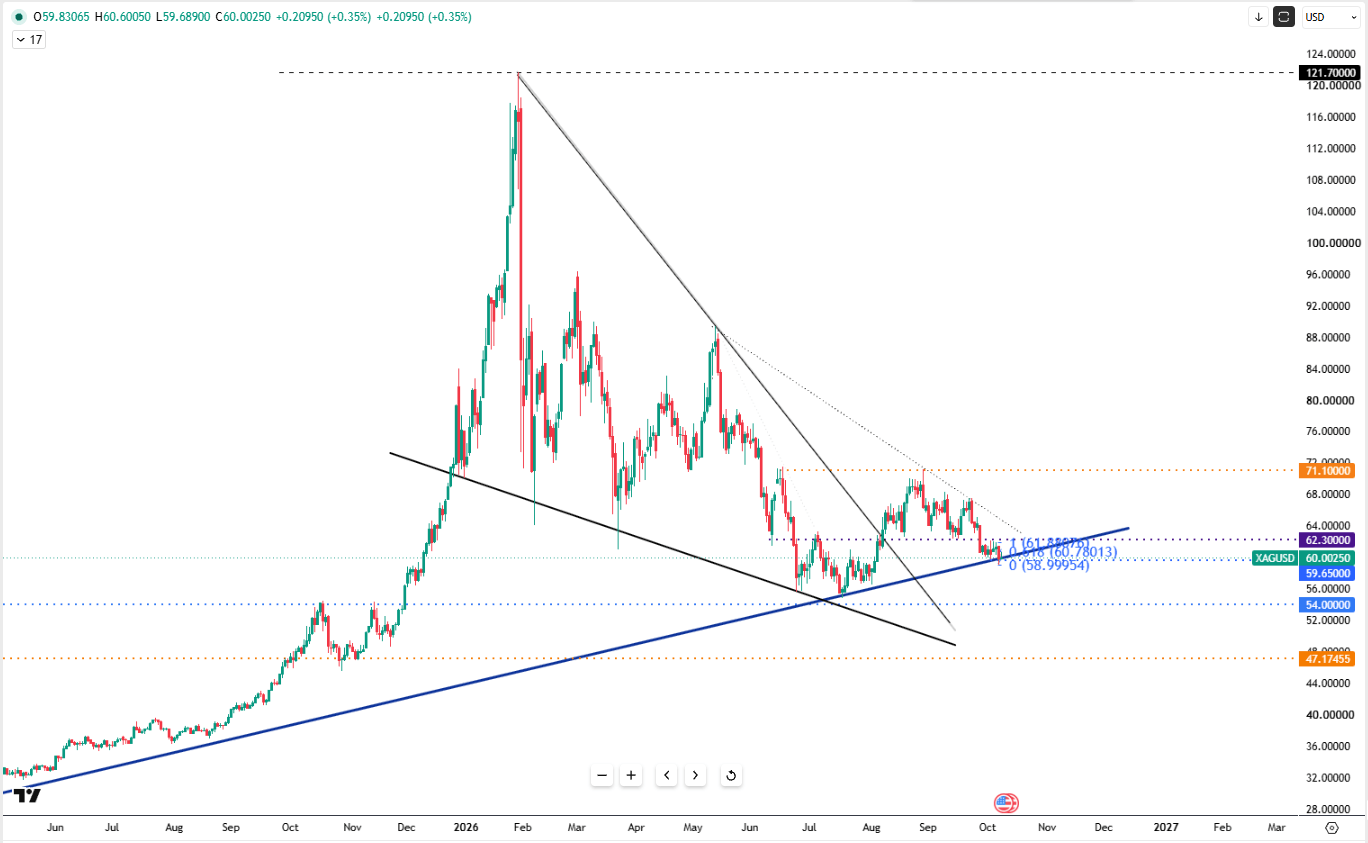
Silver held below $60 per ounce on Thursday, languishing near two-month lows. Hawkish FOMC minutes revealed unanimous backing for September's rate hike, with most officials supporting another move this year. Markets now price a 78% chance of a December hike. Rising oil prices following reports of Pentagon strike planning against Iran sustained upward pressure on inflation expectations.
From a technical view, resistance stands near $61.50, while support is located around $59,25.
| R1: 61.50 | S1: 59.25 |
| R2: 63.20 | S2: 58.40 |
| R3: 65.30 | S3: 57.50 |
Oil inventories are nearing depletion, increasing supply risks and supporting prices. Aramco estimates less than 6 billion barrels remain after over 1 billion barrels were drawn this year, while the IEA is preparing a 100-million-barrel release. The US 10-year Treasury yield stabilized near 5.31% on Wednesday, close to 24-year peaks, as markets awaited the Fed's minutes.
The dollar index steadied around 102 on Tuesday, near its highest since April 2025, as the euro weakened on French fiscal and political concerns and Spain's upcoming snap election, yet stabilized near 1.1220 after touching its lowest level since May 2025.
DetailThen Join Our Telegram Channel and Subscribe Our Trading Signals Newsletter for Free!
Join Us On Telegram!


